Does corporate America see a future in the United States?
This article was originally posted on Good Jobs First’s blog.
When the term “Rustbelt” was coined in the 1980s and activists learned the early warning signs of a plant closing, one of those indicators was tax dodging. If a company knew it was planning to close a factory, it would often challenge its property tax assessment or seek other tax breaks. And why not? If it didn’t expect to be hiring locally in the future, why should an employer care about the quality of the schools?
The national trend today looks like the Rustbelt 1980s on steroids. President Trump’s budget proposal follows the playbook that corporate lobbyists have long pushed in state legislatures: tax cuts for companies and the rich, coupled with dramatic cuts to services that benefit everyone. The resulting permanent damage to those public services begs the question: is Corporate America intentionally disinvesting, abandoning our nation?
In recent years, states and localities across the country have made drastic cuts to essential public services. Texas eliminated over 10,000 teaching jobs, and ended full-day preschool for 100,000 low-income kids. The city of Muncie, Indiana eliminated so many firefighter positions that the area of the city that fire trucks can reach within eight minutes was cut in half. In Milwaukee, budget cuts left the public transit reaching 1,300 fewer employers in 2015 than in 2001.
Investing in good construction jobs can build a better South
Last week was “infrastructure week” at the White House. On the face of it, that should be excellent news. But while the president’s rhetoric about the importance of infrastructure was on the mark, his actual plans are empty promises, given that the recently released Trump federal budget plan actually guts infrastructure.
Further, the president did not talk about the men and women who build our roads, schools, and hospitals. He did not talk about the kind of jobs his vague plans would create.
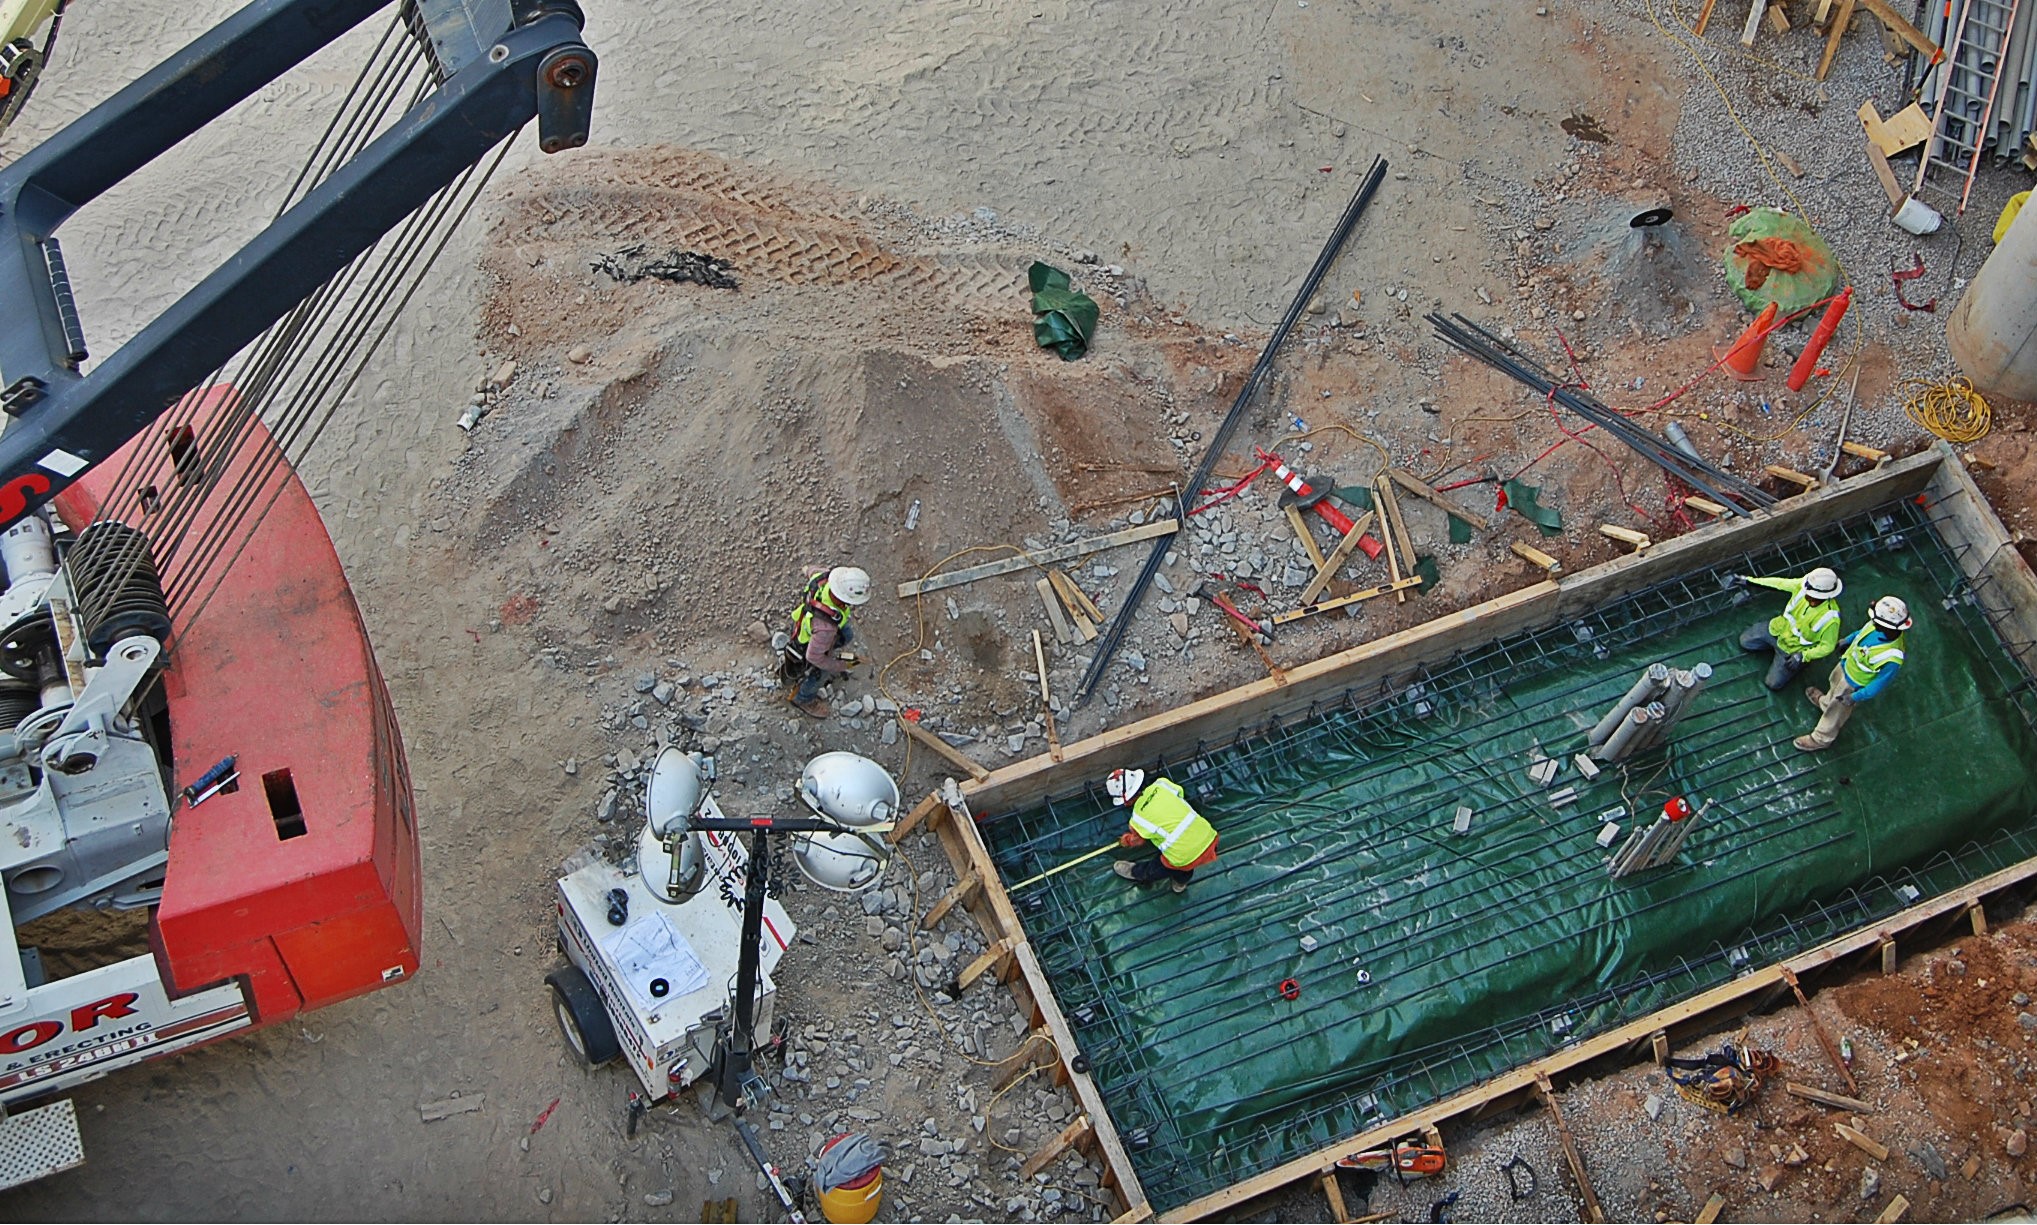
Here in the South, WDP and the EARN network think about jobs all the time. We understand that families are constantly thinking about how they will put food on the table, how they will keep a roof over their children’s heads, and maybe, just maybe, they will be able to put a little money away so they can retire at some point.
Build a Better South focuses on those families.
By rescinding the persuader rule, Trump is once again siding with corporate interests over working people
Yesterday, the Trump administration took yet another step against working people by announcing that the Department of Labor (DOL) will rescind its “persuader rule,” which would have helped level the playing field for workers by letting them know the source of the anti-union messages they receive during union drives.
Unions help union and nonunion workers in countless ways. They raise wages, make workplaces safer, and close the gender pay gap. Most importantly, unions let workers have their voices heard on the job. The ability of people to join together to negotiate for better working conditions and pay is even more important in an era of forced arbitration, where women who are sexually harassed often cannot get justice in a courtroom and workers who are being cheated out of minimum wage often cannot file class action lawsuits. All workers deserve a voice in their workplaces, and a union is one of the best ways for working people to make sure they are getting treated fairly on the job.
But many employers fight unionization efforts at every turn, by hiring professional anti-union consultants—“persuaders”—to bust their employees’ organizing drives with sophisticated anti-union campaigns. Union-busting firms promise to equip employers with “campaign strategies” and “opposition research,” and produce anti-union videos, websites, posters, buttons, T-shirts, and PowerPoint presentations for employers to deploy against their workers’ unionizing efforts. Employers spend large amounts of money to hire anti-union consultants—sometimes hundreds of thousands of dollars.
Policy Watch: Another week of weakening labor laws and making us more susceptible to a financial crisis
In the midst of a chaotic week, Congress and the Trump administration found time to quietly attack important worker protections and undermine the rules and regulations that make our economy fairer for working people and their families. Yesterday, the House passed legislation that makes our economy more susceptible to financial crises in the future, exposes consumers and investors to heightened risk of abuse in their dealings with the financial sector and rolls back the “fiduciary rule,” which requires financial advisers to act in the best interest of their clients. On Wednesday, Secretary of Labor Acosta testified in support of President Trump’s budget request for fiscal year 2018 that slashes funding for the agency that protects workers’ wages and health and safety by 20 percent. And in a symbolic anti-worker move, the Trump administration also withdrew Department of Labor guidance designed to help employers understand their obligations under the law.
Fiduciary Rule
Today, the Department of Labor regulation known as the “fiduciary rule” was officially implemented. So, all financial advisers are finally, technically required to act in the best interest of clients saving for retirement. This is a huge win for savers but, while the rule’s fiduciary standard is now in effect, it comes with a couple of catches. Important compliance provisions built into the rule’s exemptions have been delayed until January 1, 2018. DOL has made it clear that it will not enforce the rule until then, either. Until the rule has been fully implemented and is being fully enforced, retirement savers will keep losing money to unscrupulous financial advisers.
People in states represented by the cosponsors of the CHOICE Act lose $12.1 billion each year due to conflicted retirement advice
Yesterday, the Financial CHOICE Act of 2017 passed the House of Representatives along party lines, with 233 Republicans and no Democrats voting in favor of the bill, and 185 Democrats and one Republican voting against it. In the event it were to also pass the Senate and become law, the CHOICE Act would do profound, broad-based damage to the future financial security of America’s working families.
Among the many damaging things the bill does is to repeal of the Conflict of Interest rule, aka the “fiduciary” rule. The fiduciary rule is the regulation that requires that financial professionals advising retirement savers act in the best interest of their clients—like doctors and lawyers are already required to do. The rule prohibits financial advisers from doing things like steering clients into investments that provide the adviser a higher commission but provide the client a lower rate of return. This rule is sorely needed—conservative estimates put the cost to retirement savers of “conflicted” advice at $17 billion a year. It is noteworthy that today is the day that the fiduciary rule was implemented. This is a huge win for retirement savers, though this big step forward comes with a couple of glaring catches.

A couple lesser-known bits of mayhem in the Financial CHOICE Act
Today the U.S. House of Representatives begins consideration of the Financial CHOICE Act of 2017, a sweeping bill that would make a number of extensive changes to the institutions that oversee the American monetary and financial system.
The CHOICE Act is frequently (and accurately) described as an effort to undo much of the Dodd-Frank Wall Street Reform and Consumer Protection Act, which is the critical banking regulation passed under President Obama after the financial crisis of 2008/2009 to help avert future crises. The provisions in the CHOICE Act that repeal major parts of Dodd-Frank have rightly received a great deal of attention. But, there is more to the CHOICE Act than rolling back Dodd-Frank. Below we highlight two lesser-known but highly concerning components of the bill.
The CHOICE Act would make major and undesirable changes to the governance and conduct of the Federal Reserve.
The status quo of the Federal Reserve should not persist. Governance should become more transparent and representative and policy should weigh the economic interests of low and middle-wage workers more highly. But the reforms proposed in the Financial CHOICE Act go in precisely the wrong direction regarding both governance and policy conduct of the Fed.
Fed Governance
In regard to governance, the Financial CHOICE Act proposes expanding the influence of regional Federal Reserve Bank presidents on the Federal Open Market Committee (FOMC), at the expense of the Federal Reserve’s Board of Governors (BOG). Regional presidents are chosen through largely opaque processes led by regional Federal Reserve Bank boards of directors. These regional boards are dominated by financial and corporate interests. Fed Governors, conversely, are nominated by the President and must be confirmed by the Senate. This insures at least some modicum of democratic accountability. Voting rights on the FOMC are supposed to be split 7-5 in favor of the BOG (currently there are two vacancies on the BOG, so the regional banks already have parity).
The data are in…and show that the fiduciary rule will help retirement savers
As the Trump administration considers weakening the long-awaited “fiduciary rule”, industry-backed groups continue to release transparently self-serving “research” purporting to show that the rule, which protects retirement savers against sales pitches disguised as financial advice, will do more harm than good.
Most recently, the U.S. Chamber of Commerce released a report misleadingly entitled, The Data Is [sic] In: The Fiduciary Rule Will Harm Small Retirement Savers. The data actually show nothing of the kind. As the Consumer Federation of America has pointed out, even comparing a partial estimate of the harm done to savers from conflicted advice with an inflated estimate of the cost of implementing the rule shows that the rule’s benefits vastly outweigh its costs.
This hasn’t prevented the Chamber and others from claiming that the rule will harm investors by restricting access to retirement services, limiting investment options, and increasing fees paid for investment advice. These claims are based on surveys of firms with an interest in weakening or overturning the rule, conducted by industry associations and conservative groups who are in many cases ideologically opposed to government regulation. As EPI Vice President Ross Eisenbrey recently told the acting Solicitor of Labor, affected industries invariably predict dire outcomes from regulations they oppose since they are rarely called to account when their predictions prove unfounded.
Even if the industry’s questionable predictions that the rule could cause some retirement savers to experience reduced access to investment products or advice are borne out, it doesn’t follow that investors will be harmed by the fiduciary rule. The rule’s purpose is to ensure that any retirement investment advice serves the investor’s best interest, not the adviser’s self-interest. The fact that salespeople masquerading as financial planners will no longer be able to offer conflicted advice that steers people to costly products doesn’t mean investors will be harmed—to the contrary. And since bad products and services crowd out good ones, the anticipated fiduciary rule—despite the Trump administration’s delay in implementing it—has already expanded the market for low-cost investment options.
Trump’s infrastructure plans are empty promises not backed by money
It has been declared “infrastructure week” by the Trump administration. On the face of it, that should be excellent news. The U.S. economy would benefit enormously from an ambitious increase in public investment, including infrastructure investment. Such investment would create jobs and finally lock-in genuine full employment in the near-term, and would provide a needed boost to productivity growth (or how much income and output each hour of work generates in the economy) in the medium-term. Further, infrastructure investments would ensure that we do not leave future generations a deficit of underinvestment and deferred maintenance of public assets.
This clear need is why we at EPI have been such enthusiastic backers of the Congressional Progressive Caucus (CPC) plan to boost infrastructure investment. The CPC investment plan is up to the scale of the problem, and it confronts the need to make these investments head-on, without accounting gimmicks or magical thinking about where the money for these investments will come from.
Despite being long-standing and loud proponents of the need for more infrastructure investment, however, we cannot say we expect much from the Trump administration’s infrastructure week. Why not? Because the most common theme in the Trump administration’s approach to infrastructure is pure obfuscation about how it will be paid for. If you’re not willing to say forthrightly how you’re going to pay for infrastructure investments, you really cannot be serious about it. As the old adage goes, “show me your budget and I’ll tell you what you value”.
The recently released Trump federal budget plan guts infrastructure, period. Read the link—the damage the Trump budget would do to public investment and infrastructure is staggering. This alone should make any open-minded person extraordinarily skeptical of their claims to value infrastructure spending.
The Trump campaign plan on infrastructure was notable only for its shallowness and its determination to increase cronyism in infrastructure provision. The plan claimed that the problem with American infrastructure investment was a lack of innovative financing, and that the private sector could somehow be convinced to build infrastructure at no cost to taxpayers. This was obviously false. Even long-standing, bipartisan efforts to leverage private sector financing of infrastructure have ranged from disappointing to disastrous. And in no case did they provide a free lunch to taxpayers—unless taxpayers have a huge preference to paying tolls to private companies rather than the same amount of tolls or taxes to governments.
The problem holding back increased investment in American infrastructure is simple: politicians are simply unwilling to increase public spending in a transparent way. This must be overcome—America needs a significant investment in public assets, and it needs this investment to be transparent, subject to democratic accountability, and long-lived.
The sketch of the new Trump infrastructure effort included in their budget shows clearly that they do not get this. Instead, the plan is more obfuscation and magical thinking. They claim their plan will lead to $1 trillion in new investments. Yet only $200 billion in new federal spending is specified (and again, this must be balanced against the enormous cuts to public investment already embedded in their overall budget plan). Where does the rest of the funding come from? In a word, nowhere. There is hand waving about leveraging the private sector and vague claims that federal “divestment” from infrastructure provision will somehow empower state and local governments to do more (but without any new funding source for these governments!). But like Trump’s campaign plan, this is an unserious document meant to sound like an infrastructure investment plan, but one that would radically underinvest in projects overall, and which would prioritize projects that can provide profits to private entities (like toll roads to airports) rather than projects that provide the largest welfare boost to vulnerable communities (say replacing lead-laced water pipes for communities like Flint, Michigan).
As the Trump administration kicks off “infrastructure week”, remember that its recent budget is an absolute disaster for public investment
Back in March, the Trump administration released its “skinny” budget. The skinny budget laid out the administration’s priorities for the next two years of discretionary spending. This skinny budget made absolutely disastrous cuts to nondefense discretionary (NDD) spending. This matters to most Americans because the NDD portion of the budget is where the vast majority of public investment is funded.
NDD spending is already on an extraordinarily austere path under current law. The Congressional Budget Office (CBO) estimates that by 2027 NDD budget authority as a percentage of GDP will fall by one-fifth, reaching a historic low of 2.4 percent. Trump’s skinny budget wanted us to get to this anemic level by next year.
And the details of the recently released full ten-year budget are far worse.
The Trump administration’s budget would cut NDD budget authority as a percentage of GDP by 56 percent, slashing it to an unprecedented 1.4 percent of GDP by 2027. CBO estimates that NDD spending will account for just 13 percent of all federal spending over the next ten years, but half of it is public investment. The full Trump budget would be an unprecedented disaster for public investment.
Historical and projected nondefense discretionary budget authority as a percentage of GDP, FY1976—FY2027
| Year | President’s Budget | CPC budget | Historic | Current Law | Historical Average* |
|---|---|---|---|---|---|
| 1976 | 5.60% | 3.53% | |||
| 1977 | 6.73% | 3.53% | |||
| 1978 | 6.26% | 3.53% | |||
| 1979 | 5.80% | 3.53% | |||
| 1980 | 5.96% | 3.53% | |||
| 1981 | 5.11% | 3.53% | |||
| 1982 | 4.18% | 3.53% | |||
| 1983 | 4.05% | 3.53% | |||
| 1984 | 4.00% | 3.53% | |||
| 1985 | 3.79% | 3.53% | |||
| 1986 | 3.27% | 3.53% | |||
| 1987 | 3.30% | 3.53% | |||
| 1988 | 3.12% | 3.53% | |||
| 1989 | 3.07% | 3.53% | |||
| 1990 | 3.26% | 3.53% | |||
| 1991 | 3.50% | 3.53% | |||
| 1992 | 3.61% | 3.53% | |||
| 1993 | 3.64% | 3.53% | |||
| 1994 | 3.48% | 3.53% | |||
| 1995 | 3.14% | 3.53% | |||
| 1996 | 2.96% | 3.53% | |||
| 1997 | 2.89% | 3.53% | |||
| 1998 | 2.87% | 3.53% | |||
| 1999 | 3.09% | 3.53% | |||
| 2000 | 2.79% | 3.53% | |||
| 2001 | 3.14% | 3.53% | |||
| 2002 | 3.44% | 3.53% | |||
| 2003 | 3.48% | 3.53% | |||
| 2004 | 3.50% | 3.53% | |||
| 2005 | 3.78% | 3.53% | |||
| 2006 | 3.22% | 3.53% | |||
| 2007 | 3.14% | 3.53% | |||
| 2008 | 3.35% | 3.53% | |||
| 2009 | 5.53% | 3.53% | |||
| 2010 | 3.72% | 3.53% | |||
| 2011 | 3.32% | 3.53% | |||
| 2012 | 3.29% | 3.53% | |||
| 2013 | 3.27% | 3.53% | |||
| 2014 | 3.07% | 3.53% | |||
| 2015 | 2.98% | 3.53% | |||
| 2016 | 3.05% | 3.05% | 3.05% | 3.05% | 3.53% |
| 2017 | 2.80% | 2.88% | 2.88% | 3.53% | |
| 2018 | 2.40% | 3.14% | 2.75% | 3.53% | |
| 2019 | 2.25% | 3.25% | 2.71% | 3.53% | |
| 2020 | 2.10% | 3.34% | 2.69% | 3.53% | |
| 2021 | 1.93% | 3.45% | 2.65% | 3.53% | |
| 2022 | 1.82% | 3.53% | 2.62% | 3.53% | |
| 2023 | 1.71% | 3.53% | 2.58% | 3.53% | |
| 2024 | 1.61% | 3.53% | 2.54% | 3.53% | |
| 2025 | 1.52% | 3.53% | 2.51% | 3.53% | |
| 2026 | 1.43% | 3.53% | 2.47% | 3.53% | |
| 2027 | 1.35% | 3.53% | 2.44% | 3.53% |
*Historical average reflects the average nondefense discretionary budget authority as a share of GDP between FY1980 and FY2007 (the last year before the onset of the Great Recession).
Notes: For the president's budget, this figure uses CBO's projections of GDP. Data for 2016 represent actual spending. Data for 2017 exclude CHIMPs.
Source: EPI Policy Center analysis of Congressional Budget Office and Office of Management and Budget data.
This highlights the enormous gap between Trump administration rhetoric about boosting infrastructure investment and the reality of their policies. Trump campaigned on a $1 trillion infrastructure proposal, but has never backed this up with a real plan. First, the campaign’s original plan was simply not serious, and would not have led to anywhere near $1 trillion in net new investment forthcoming. Next, the skinny budget cut the Department of Transportation by 13 percent. And these are not just cuts to some abstract bureaucracy, included are cuts to actual infrastructure funding. About 21 percent of those cuts come from ending the TIGER discretionary grants program that fund state-level infrastructure projects.
Unemployment rate fell in May for the wrong reasons: Slack still remains
The latest data from the Bureau of Labor Statistics reveals a noticeable slowdown in job growth this year. Adding in May’s 138,000 net new jobs, monthly job growth averaged 162,000 so far in 2017, and just 121,000 over the last three months, down from an average monthly gain of 187,000 jobs in 2016. While employment growth would be expected to slow as the economy approaches genuine full employment, other indicators suggest we are not that close to full employment yet, so this explanation seems insufficient. Specifically, at this point in the recovery, we should be looking to not only add jobs, but also see stronger wage growth in those jobs.
But this is not what we’ve seen. Unfortunately, wage growth has been flat over the last year. The latest data indicates that year-over-year nominal hourly wages grew 2.5 percent in May. In fact, as shown in the figure below, wage growth has averaged 2.5 percent over the last two years. If anything, we’ve seen a bit of a slowdown in wage growth this spring, and it is still below levels consistent with the Federal Reserve’s 2 percent inflation target combined with trend productivity growth of 1.5 percent. So, why has wage growth continued to be below target levels after recovery has gone on so long? The simple answer is that while the recovery has been long, it has also been weak. And this weakness combined with the extraordinary damage done during the Great Recession means that slack remains.
Nominal wage growth has been far below target in the recovery: Year-over-year change in private-sector nominal average hourly earnings, 2007–2017
| Date | All nonfarm employees | Production/nonsupervisory workers |
|---|---|---|
| Mar-2007 | 3.44% | 4.17% |
| Apr-2007 | 3.13% | 3.85% |
| May-2007 | 3.53% | 4.14% |
| Jun-2007 | 3.61% | 4.13% |
| Jul-2007 | 3.25% | 4.05% |
| Aug-2007 | 3.35% | 4.04% |
| Sep-2007 | 3.09% | 4.09% |
| Oct-2007 | 3.03% | 3.72% |
| Nov-2007 | 3.07% | 3.89% |
| Dec-2007 | 2.92% | 3.75% |
| Jan-2008 | 2.91% | 3.80% |
| Feb-2008 | 2.85% | 3.79% |
| Mar-2008 | 3.04% | 3.71% |
| Apr-2008 | 2.89% | 3.70% |
| May-2008 | 3.07% | 3.69% |
| Jun-2008 | 2.67% | 3.62% |
| Jul-2008 | 3.05% | 3.67% |
| Aug-2008 | 3.33% | 3.89% |
| Sep-2008 | 3.28% | 3.70% |
| Oct-2008 | 3.32% | 3.93% |
| Nov-2008 | 3.50% | 3.80% |
| Dec-2008 | 3.59% | 3.90% |
| Jan-2009 | 3.58% | 3.72% |
| Feb-2009 | 3.43% | 3.65% |
| Mar-2009 | 3.28% | 3.53% |
| Apr-2009 | 3.37% | 3.35% |
| May-2009 | 2.93% | 3.11% |
| Jun-2009 | 2.88% | 2.88% |
| Jul-2009 | 2.69% | 2.76% |
| Aug-2009 | 2.44% | 2.64% |
| Sep-2009 | 2.44% | 2.75% |
| Oct-2009 | 2.53% | 2.68% |
| Nov-2009 | 2.15% | 2.73% |
| Dec-2009 | 1.96% | 2.50% |
| Jan-2010 | 2.09% | 2.66% |
| Feb-2010 | 2.09% | 2.55% |
| Mar-2010 | 1.81% | 2.27% |
| Apr-2010 | 1.81% | 2.38% |
| May-2010 | 1.90% | 2.54% |
| Jun-2010 | 1.76% | 2.53% |
| Jul-2010 | 1.85% | 2.42% |
| Aug-2010 | 1.75% | 2.36% |
| Sep-2010 | 1.84% | 2.19% |
| Oct-2010 | 1.93% | 2.51% |
| Nov-2010 | 1.79% | 2.18% |
| Dec-2010 | 1.74% | 2.02% |
| Jan-2011 | 1.92% | 2.17% |
| Feb-2011 | 1.83% | 2.06% |
| Mar-2011 | 1.83% | 2.06% |
| Apr-2011 | 1.87% | 2.11% |
| May-2011 | 2.04% | 2.05% |
| Jun-2011 | 2.13% | 2.05% |
| Jul-2011 | 2.30% | 2.26% |
| Aug-2011 | 1.95% | 1.99% |
| Sep-2011 | 1.94% | 1.99% |
| Oct-2011 | 2.07% | 1.72% |
| Nov-2011 | 1.98% | 1.82% |
| Dec-2011 | 2.07% | 1.87% |
| Jan-2012 | 1.79% | 1.40% |
| Feb-2012 | 1.79% | 1.45% |
| Mar-2012 | 2.14% | 1.71% |
| Apr-2012 | 2.09% | 1.65% |
| May-2012 | 1.74% | 1.44% |
| Jun-2012 | 1.96% | 1.54% |
| Jul-2012 | 1.69% | 1.33% |
| Aug-2012 | 1.86% | 1.33% |
| Sep-2012 | 1.99% | 1.38% |
| Oct-2012 | 1.51% | 1.28% |
| Nov-2012 | 1.94% | 1.43% |
| Dec-2012 | 2.11% | 1.58% |
| Jan-2013 | 2.06% | 1.89% |
| Feb-2013 | 2.19% | 2.04% |
| Mar-2013 | 1.88% | 1.88% |
| Apr-2013 | 1.97% | 1.78% |
| May-2013 | 2.14% | 1.93% |
| Jun-2013 | 2.17% | 2.03% |
| Jul-2013 | 2.04% | 2.03% |
| Aug-2013 | 2.26% | 2.23% |
| Sep-2013 | 2.08% | 2.28% |
| Oct-2013 | 2.25% | 2.27% |
| Nov-2013 | 2.20% | 2.37% |
| Dec-2013 | 1.98% | 2.26% |
| Jan-2014 | 2.02% | 2.31% |
| Feb-2014 | 2.23% | 2.50% |
| Mar-2014 | 2.14% | 2.35% |
| Apr-2014 | 2.01% | 2.40% |
| May-2014 | 2.13% | 2.44% |
| Jun-2014 | 2.00% | 2.34% |
| Jul-2014 | 2.09% | 2.38% |
| Aug-2014 | 2.21% | 2.43% |
| Sep-2014 | 2.04% | 2.27% |
| Oct-2014 | 2.03% | 2.27% |
| Nov-2014 | 2.03% | 2.21% |
| Dec-2014 | 1.86% | 1.92% |
| Jan-2015 | 2.19% | 2.01% |
| Feb-2015 | 1.93% | 1.61% |
| Mar-2015 | 2.22% | 2.00% |
| Apr-2015 | 2.26% | 2.00% |
| May-2015 | 2.30% | 2.14% |
| Jun-2015 | 2.09% | 1.99% |
| Jul-2015 | 2.21% | 2.04% |
| Aug-2015 | 2.24% | 2.08% |
| Sep-2015 | 2.32% | 2.13% |
| Oct-2015 | 2.56% | 2.32% |
| Nov-2015 | 2.39% | 2.12% |
| Dec-2015 | 2.52% | 2.56% |
| Jan-2016 | 2.51% | 2.45% |
| Feb-2016 | 2.38% | 2.45% |
| Mar-2016 | 2.45% | 2.44% |
| Apr-2016 | 2.61% | 2.58% |
| May-2016 | 2.52% | 2.33% |
| Jun-2016 | 2.64% | 2.52% |
| Jul-2016 | 2.76% | 2.61% |
| Aug-2016 | 2.55% | 2.46% |
| Sep-2016 | 2.75% | 2.65% |
| Oct-2016 | 2.74% | 2.50% |
| Nov-2016 | 2.65% | 2.50% |
| Dec-2016 | 2.85% | 2.54% |
| Jan-2017 | 2.56% | 2.39% |
| Feb-2017 | 2.84% | 2.48% |
| Mar-2017 | 2.63% | 2.34% |
| Apr-2017 | 2.51% | 2.38% |
| May-2017 | 2.46% | 2.42% |
*Nominal wage growth consistent with the Federal Reserve Board's 2 percent inflation target, 1.5 percent productivity growth, and a stable labor share of income.
Source: EPI analysis of Bureau of Labor Statistics Current Employment Statistics public data series
But, you say, the unemployment rate fell to 4.3 percent in May, its lowest in 16 years! Unfortunately, the unemployment rate fell for the wrong reasons and isn’t fully reflective of the state of the labor market. That is, in the past when unemployment was roughly as low as it is today, the labor force participation rate—notably that of the prime-age population—has been much higher. Today, there are lots of would-be workers on the sidelines not being counted, who would take a job if offered one. And, the drop in the unemployment rate in the past month is more of a sign of people giving up on finding a job than more people becoming employed. In the last month, the labor force participation rate fell 0.2 percentage points and the employment-to-population ratio also fell 0.2 percentage points. Taken together, that means that the slight drop in the unemployment rate is, in fact, due to would-be workers leaving the labor force, not getting jobs.