The Fed Should Continue Its Support for a Jobs Recovery
The following is a slightly edited version of remarks delivered on an Economic Policy Institute teleconference on Friday, July 25, 2014.
Since the Great Recession began almost 7 years ago, the Fed has been the most proactive and the most effective macroeconomic policy-making institution both in attempting to end the recession and then subsequently trying to spur a full recovery. It’s been the most effective by far in the United States and almost certainly the most effective in the world. The Fed deserves a lot of praise for this stance and the economic evidence argues strongly that it should continue to prioritize boosting employment and spurring a full economic recovery. Specifically, this evidence indicates:
- The economy continues to have enormous amounts of productive slack—including in the labor market.
- Until this slack is taken up, wage-driven inflationary pressures just will not materialize.
- Wage and compensation growth will have to more than double to put significant upward pressure on overall price-growth in coming years—meaning that the Fed should be fully comfortable with nominal compensation growth as high as 4 percent over the next couple of years. This follows from the fact that trend productivity growth is roughly 1.5 percent so that 2.0 to 2.5 percent nominal compensation growth above 1.5 percent implies rising unit labor costs corresponding to 2.0 percent inflation, allowing for an additional to 0.5 compensation growth at the expense of historically thick profit margins.
The Fed is commonly described as being tasked with targeting more rapid employment growth and economic activity until the point that such rapid growth begins to spur accelerating inflation. The U.S economy is nowhere near the point where growth is rapid enough to spark accelerating inflation. Instead, we remain far from fully recovered from the Great Recession, and because of this, inflationary pressures just aren’t in the data.
What’s at Stake If the Fed Prematurely Raises Rates
The following is a slightly edited version of remarks delivered on an Economic Policy Institute teleconference on Friday, July 25, 2014.
Any systematic look at the current data on the U.S. labor market says that the large costs of the incomplete recovery are quite apparent. We still have a labor market that faces three major ongoing problems. The first is that our very incomplete macroeconomic recovery means that we have continuing high cyclical non-employment and a lot of slack left in the labor market. Even if you look at prime-age workers, those 25 to 54 years old, we’re only one-third of the way back in terms of the employment rate to where we were before the Great Recession.
If you look at young workers, the situation is particularly dire. We still have close to record low employment rates for those less than 25 years old. For disadvantaged and minority young men, the fraction that are both out of school and out of work has increased enormously since 2007; for young black males aged 20 to 24 by almost 10 percentage points from about 23 percent to 32 percent. Over the last year, we are finally seeing some significant recovery in employment, but it’s not nearly enough yet to make people whole and create real opportunities for those in many low-income and working-class communities.
Second, even as we get back closer to full employment, from which we remain very far from, we will still have the scars of the Great Recession including huge increases in the long-term unemployed and in disconnected young workers who have not gotten the types of opportunities needed to jump start their careers and to be poised to move up the career ladder in a stronger economy. So we will need to run a tight labor market for longer than normal—possibly even allowing inflation to eventually overshoot the Fed’s target for a modest period as suggested in a recent paper by Glenn Rudebusch and San Francisco Fed President John Williams—just to help make many American families whole once again and to make enough progress in combating long-term unemployment.
What You Need to Know about the President’s Legal Authority to Expand Deferred Action for Unauthorized Immigrants
President Obama is reportedly considering “deferring” (temporarily suspending) the deportation of up to five million unauthorized immigrants, which would expand and be modeled after his 2012 Deferred Action for Childhood Arrivals (DACA) initiative. This has led to a stimulating and lively public discussion regarding the extent of the president’s legal authority under U.S. immigration law. Understanding the basics of what the president may or may not do under existing law, his constitutional authority and responsibilities, and what Congress can do about it if it disapproves of the president’s course of action, is essential for evaluating the various policy arguments and should help non-lawyers follow the many nuances of this substantive debate.
Here are four questions and answers to get you up to speed:
1. Does the president have legal authority to defer the deportation of all unauthorized immigrants?
No. The president cannot refuse to enforce immigration laws, or enforce an immigration law in a way that is contrary to the aims of the law, or change immigration policy on his own. This requirement comes from the “Take Care” clause in the U.S. Constitution, which requires the president to ensure “that the Laws be faithfully executed” (Article II, Section 3). The Immigration and Nationality Act, the United States’ main set of immigration laws, contains many provisions specifying who is a “removable” (i.e., deportable) migrant (the term the law uses is “alien”). Right now there are an estimated 11.7 million unauthorized immigrants in the United States, who are deportable unless they can prove that they deserve to remain in the country because they are entitled to a legal status under U.S. law.
Congress provides the executive branch the funds to enforce the immigration laws, but it has not provided nearly enough funding to deport all 11.7 million unauthorized immigrants. The Department of Homeland Security (DHS) believes that the amount Congress has appropriated is enough to deport approximately 400,000 unauthorized immigrants per year (3.4 percent of the total) and that is how many people the Obama administration has been deporting. If the president were to refuse to deport any unauthorized immigrants, such action would violate his constitutional duty to faithfully execute the laws and amount to a de facto legalization in direct contradiction of what Congress has required of the president.
Read more
A Step in the Right Direction: OMB Will Not Implement Plan to Include “Factoryless Goods Producers” In Manufacturing
Last week, the Office of Management and Budget (OMB) announced that it was cancelling plans to reclassify factoryless goods producers (FGPs) such as Apple and Nike—most of which are now in wholesaling or management of companies (both service industries)—into manufacturing. The FGP proposal is part of a broader set of changes to the North American Industry Classification System (NAICS) that were scheduled to take effect in 2017. The FGP plan would have also required government agencies to move trade in goods made by manufacturing service providers (MSPs), such as China’s Foxconn (which builds Apple products) into services. The OMB proposal was highly controversial, and more than 26,000 comments were submitted for the record. In addition, more than 40 members of the House and Senate signed letters to the OMB raising objections and requesting clarification on a number of unresolved issues regarding the proposal.
In a recent policy memo, I noted that the proposal would artificially inflate manufacturing output and employment by treating outsourced production as part of domestic manufactured output, while artificially suppressing the reported U.S. goods trade deficit, with offsetting reductions in the services trade surplus. The proposal would also require manufacturing firms to begin reporting trade and manufacturing activities on a value-added basis, which would introduce a new level of distortion in U.S. international trade statistics that would undermine enforcement of U.S. fair trade laws. Finally, adoption of the FGP proposal, as initially formulated, could undermine U.S. Buy American Laws and U.S. Export-Import Bank policies.
The Top 10 Myths About Social Security
In honor of Social Security’s 79th birthday, here’s an update to a 2011 blog post refuting Social Security myths spread by critics of the program.
- Social Security costs are escalating out of control. No. Costs are projected to rise from roughly five to six percent of GDP before leveling off.
- Americans want benefits but aren’t willing to pay for them. Wrong again. Americans across political and demographic lines support paying Social Security taxes and prefer raising taxes over cutting benefits as a way to close the projected shortfall. A popular option is raising taxes on high earners, since earnings above $117,000 aren’t taxed. But Americans prefer to close the gap on the revenue side even if they’re asked to pay more themselves.
- Our children and grandchildren will drown in debt if we don’t cut the social safety net. No, future generations will drown in debt if we don’t address health cost inflation. Though the Affordable Care Act and other factors have slowed costs considerably, this isn’t enough—we need to get costs closer in line with those in Europe and Canada. Cutting Medicare or Medicaid benefits just pushes costs onto the private sector. And there’s no reason to lump Social Security in with other programs since it’s funded through dedicated taxes and prohibited by law from borrowing.
- The Baby Boomers will sink us. On the contrary. We saw them coming. Social Security began building up a trust fund in the early 1980s in anticipation of the Boomer retirement. The trust fund is projected to keep growing for another five years to almost $3 trillion, not quite enough to get us through the peak Boomer retirement years (the Great Recession took a bite). Read more
What’s Lost in the Market Basket Stories
The saga that has unfolded at the New England grocery store Market Basket over the past few weeks has struck a nerve, and rightly so. As many others have pointed out, the story of a corporate board taking steps to squeeze customers and employees in order to generate ever-higher profits feels far too representative of the way most businesses operate today. What fewer have come out and said: it doesn’t have to be this way.
For the uninitiated in this story, Market Basket is a supermarket chain with 71 stores in Massachusetts, Maine, and New Hampshire. The company employs about 25,000 people throughout the region and had $4.6 billion in revenue in 2013. The chain is an unabashed success, having grown from a small family store to a regional powerhouse. And they have succeeded by taking a distinctly high-road approach: the company takes care of its workers, paying decent wages, offering benefits to full- and part-time staff, and providing employees with a profit-sharing plan. At the same time, Market Basket still offers prices lower than its competitors, Walmart included.
This take-care-of-your-customers and value-your-workers philosophy has given Market Basket an intensely dedicated following, both from employees and regular shoppers. Thus, it should not be surprising that when the controlling members of the chain’s board fired the company’s beloved CEO, allegedly so that they could cut back on compensation, maximize payouts to shareholders, and potentially liquidate the company, the Market Basket faithful revolted, with workers walking off the job and customers boycotting.
I Can’t Tolerate the Nonsense on Corporate Tax Reform Any More
Corporations are adopting a new tactic to lower their taxes—renouncing their U.S. “citizenship” and adopting headquarters where there are lower tax rates. These are called “inversions.” Nothing changes in the corporations’ operations, but the “paper changes” result in lower taxes. Inversions are threatening to erode corporate taxation even further than has already occurred, which is a lot.
Corporate spokespeople would have you believe that the real problem is our corporate tax code, which they claim is in real need of “reform.” This is a total distraction, and also total nonsense.
Here’s what John Engler of the Business Roundtable said about the wave of corporations renouncing their citizenship, similar to many other quotes from business folks readily available (you can hear that same mantra from the Washington Post editorial team):
“We’re seeing one more manifestation of why the business tax structure needs to be fixed. We’re the proverbial frog that’s being boiled, and a few frogs have decided to jump out.”
The Neoliberal Mind at Work: Brad DeLong’s Muddled Defense of NAFTA
Brad DeLong recently criticized an op-ed I wrote about the negative impact of the twenty-year-old North American Free Trade Agreement on American workers.
The stakes here are higher and more immediate than the rehash of an old ideological dispute. This is not so much about the past as about the future. Corporate lobbyists are pushing President Obama and congressional Republicans to pass the NAFTA-like eleven-country Trans-Pacific Partnership” (TPP)—right after the November election.
Since it took effect in 1994, NAFTA has been the template for the subsequent series of trade agreements that have accelerated the globalization of the U.S. economy. But its failure to deliver as promised has soured the public and many in Congress on so-called “free trade.” Getting lawmakers to swallow the TPP will be easier if its promoters can somehow make lemonade out of the NAFTA lemon.
To start with, DeLong fails to tell the reader that he is evaluating a law he helped to produce. He worked on NAFTA when he was a deputy assistant secretary in Bill Clinton’s Treasury Department.
There are two parts to DeLong’s critique. One is his attempt to prove NAFTA was a success. The other is a series of gratuitous remarks about me and what he calls the “American left” that he sprinkles from his lofty pinnacle of ignorance about both.
Brad Delong’s Case for NAFTA: Based on Assumptions, Not on Data
Writing at the Equitable Growth blog, Brad DeLong takes on Jeff Faux’s assessment of NAFTA. DeLong tries to make a “cosmopolitan” argument for NAFTA; he claims that NAFTA cost the United States fewer than 350,000 jobs, and says that Faux got “the analysis wrong” when he reported that NAFTA resulted in a net loss of 700,000 jobs. But DeLong’s “analysis” is based on faulty data. He then goes on to assert that the jobs gained through increased exports pay more than the jobs lost due to growing imports, which also turns out to be wrong. Lastly, he ignores the larger and much more important negative impact of growing trade with low-wage countries on the wages of all U.S. workers without a college degree.
President Bill Clinton and the economists he relied on built their case for NAFTA on the assertion that the United States would gain jobs as a direct result of the agreement. He claimed that NAFTA would create an “export boom to Mexico” that would create 200,000 jobs in two years and a million jobs in five years, “many more jobs than will be lost” due to rising imports. This is the central argument used to justify NAFTA by its proponents, so it’s entirely appropriate to evaluate its impact by examining its net impacts on U.S. employment.
The economic logic behind Clinton’s argument was clear: Trade creates new jobs in exporting industries and destroys jobs when imports replace the output of domestic firms. Exports support domestic jobs and production, and imports displace domestically produced goods, displacing existing jobs and preventing new job creation. Clinton assumed, without much evidence, that the net employment effect would be positive. But unfortunately, it wasn’t.
DeLong begins his jobs analysis by noting that trade would have grown with or without NAFTA. But this ignores the status quo ante. U.S.-Mexico trade was roughly balanced in the pre-NAFTA period. If exports and imports had both doubled, our bilateral trade would still have been balanced. Instead, imports grew faster than exports, so the United States developed a significant, job destroying trade deficit with Mexico. We differ over the size of this effect, which I’ll get to in a moment, but the key question is why that trade deficit developed. As I’ve shown elsewhere, the growth of outsourcing, and a near-tripling of foreign direct investment (FDI) in Mexico, were the principle causes. NAFTA created a unique set of investor protections that encouraged multinationals to shift production from the United States to Mexico. The growth of FDI in Mexico overshadowed any impact of tariff cuts (which were larger in Mexico than the United States).
DeLong develops ballpark estimates of the numbers of jobs gained and displaced by U.S. trade with Mexico after NAFTA, using gross trade data from the St. Louis Fed for total U.S. exports and imports of goods to and from Mexico. I have estimated that trade deficits with Mexico displaced 682,900 U.S. jobs in 2010 (the United States had a small trade surplus with Mexico in 1993, before NAFTA took effect, so our best estimate is that growing trade deficits displaced about 700,000 U.S. jobs between 1993 and 2010, as noted by Faux). Our analysis is based on trade data from the U.S. International Trade Commission (USITC) and an employment requirement matrix from the U.S. Bureau of Labor Statistics.
My estimates of the jobs supported by U.S. exports are based only on U.S. domestic exports to Mexico—goods produced in the United States with U.S. labor. Total exports also include a growing share of transshipments, or foreign exports (aka re-exports), goods produced in other countries (e.g., China) that are imported into the United States and re-exported to other countries (e.g., Mexico). Foreign exports do not support domestic employment. Data on transshipments are almost always excluded from analyses of the impacts of trade and trade agreements, such as those prepared by the USITC, as noted by agency economists. And the exclusion of transshipments makes a big difference in NAFTA trade, as shown in the graph below (my jobs analysis is also based on imports for consumption rather than general imports, but this distinction has no significant impact on job loss estimates).
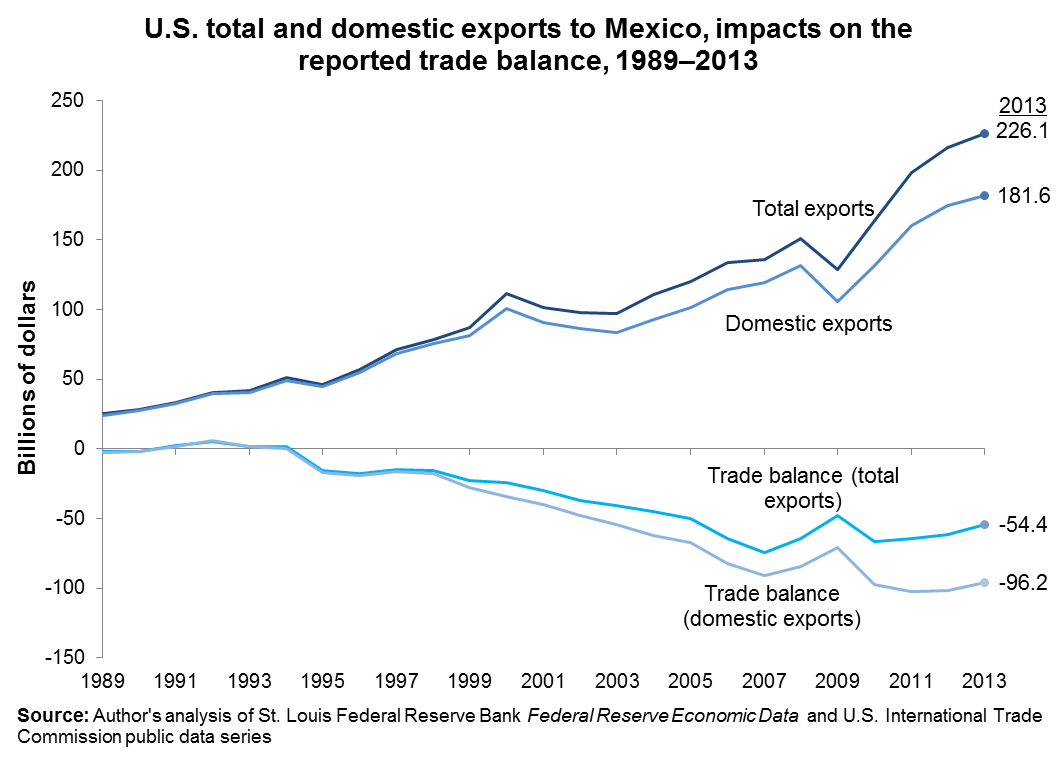
U.S. exports to Mexico, both total and domestic, have increased since NAFTA took effect, but the gap between them (i.e., foreign exports) has increased much more rapidly. Imports (not shown) have also increased faster than exports, and as a result, the U.S. trade deficit with Mexico has increased steadily since NAFTA took effect.
The U.S.-Mexico trade deficit in 2013 (and hence the jobs displaced by trade) when properly calculated, using domestic exports, was $96.2 billion, nearly twice as large as the deficit estimated with total U.S. exports ($54.4 billion). The difference in estimated trade balances largely explains why my estimate of the jobs displaced by NAFTA (700,000) is twice as large as DeLong’s (350,000). The centerpiece of his critique of Faux’s analysis is based on faulty data, but that’s just where the problems begin.
Job losses are just the tip of the iceberg for domestic workers
DeLong asserts that even if NAFTA did result in job losses, some workers gained because the jobs gained through increased exports are “better jobs with higher pay” than the jobs lost due to higher imports. But this assertion is not backed up with any data. I have compared jobs created and displaced by NAFTA and found that the facts do not support this assumption. In a 2006 report I showed that jobs displaced by imports from Mexico paid $813 per week, while jobs supported by exports to Mexico paid only $799 per week, 1.8% percent less. More importantly, with respect to the 700,000 net jobs lost, even when re-employed in non-traded industries, workers earned only $683 per week, 19 percent less than the jobs displaced by imports. Wage losses associated with trading good jobs in import-competing industries for lower paying jobs in exporting and non-traded goods industries cost U.S. workers $7.6 billion in 2004.
My results for Mexico trade are not anomalous. I found similar and even stronger results for U.S.-China trade. Average weekly wages of jobs displaced by imports from China between 2001 and 2011 were 17.0 percent higher than average wages in jobs supported by exports to China. Workers in non-traded industries earned 9.4% less than workers in exporting industries. Growing trade deficits with China cost 2.7 million jobs between 2001 (which China entered the WTO) and 2011, resulting in $37 billion in lost wages in 2011 alone.
The analysis of wages paid to workers in import, export and non-traded industries holds everything else constant. It does not reflect the much more important, economy-wide impacts of trade on the wages of working Americans, the well-known Stolper-Samuelson effects. Direct wage losses for workers displaced by NAFTA and China trade are just indicative of the larger impact of trade on wages for working Americans. Most traded goods are manufactured products, production of which disproportionately employs non-college-educated workers. Trade with low-wage countries like Mexico and China puts manufacturing workers, and everyone with a similar skill set, into competition with low-wage workers abroad.
Josh Bivens has shown that growing trade with less developed countries (LDCs) has been responsible for large shares of the rapidly growing college–non-college wage gap. That overall wage gap increased 22.0 percentage points between 1979 and 2011. Bivens’ model estimates the broad impacts of trade on all non-college educated workers in the United States, who number about 100 million. His study shows that growing LDC trade “lowered wages in 2011 by 5.5 percent—or by roughly $1,800—for a full-time, full-year worker earning the average wage” for such workers. Trade with low-wage countries can explain roughly a third of the overall rise since 1979 in the wage premium earned by workers with at least a four-year college degree relative to those without one. However, trade with low-wage countries explains more than 90 percent of the rise in this premium since 1995. China and Mexico are the United States’ two largest low-wage trade partners.
It’s important to note that trade was not the only cause of growing inequality over the past three decades or so (since the late 1970s). Growing inequality in this era was the result of policy choices on behalf of corporate interests including macroeconomic policy (e.g., too-tight monetary policy leading to an increase in average unemployment levels), trade agreements, deregulation of the financial sector, attacks on the legal foundations of organized labor, declines in the real minimum wage, deregulation of many industries and privatization of the public sector, and other policies that have helped some workers and hurt others. Many economists and policy makers blame technology instead (more specifically, skill biased technical change), but there is mounting evidence against this view. Rapid technological progress has been a hallmark of the American economy for generations, but massive growth in inequality began only in the late 1970s, and is strongly correlated with the policy choices noted above.
DeLong argues that the United States, as a “hyperpower,” has a “strong moral obligation to the world” as a whole to support trade and investment deals like NAFTA. We can certainly agree that NAFTA was a much bigger deal for Mexico than it was for the United States. But it was a bad deal for Mexico. DeLong asserts that NAFTA “boosted employment in Mexico by 1.5 million” (3 percent of the Mexican labor force). But most of the jobs gained must have been in manufacturing, since about 80% of Mexico’s exports are manufactured products. However, Mexico only added about 400,000 manufacturing jobs between 1993 and 2013, and this is probably an overestimate of the employment gains from trade because it doesn’t take into account job losses in Mexican agriculture due to opening of grain trade. Furthermore, rates of growth in per capita GDP in Mexico fell from 3 percent per year in the period between the 1940s and the 1970s to 1 percent after it liberalized trade in the late 1980s and then joined NAFTA. Again, the data conflict with DeLong’s theoretical assumptions. If NAFTA was a bad deal for workers in Mexico, why should policymakers in the United States support trade and investment deals that cost jobs and reduce wages for most working Americans?
DeLong expresses consternation at the “energy the American left poured and pours into the anti-NAFTA cause.” He, of course, is energetically still trying to defend policies that he supported while serving as a deputy assistant secretary of the U.S. Treasury between 1993 and 1995, when NAFTA (and the WTO) were created. But it’s clear that NAFTA failed to measure up to the claims on which it was sold to the American people and to Congress and has been a significant contributor to growing inequality, one of the most pernicious problems of the past two decades. Furthermore, DeLong does not dispute the fact that NAFTA cost jobs in the United States, and only quibbles about the numbers. This only raises the question, if trade hurts the domestic economy, why should we supercharge it?
DeLong also argues that if NAFTA increased unemployment and lowered wages, then we should just fix our macroeconomic policies, including “exchange rate policies” to change them. But this illustrates just how flawed NAFTA was—a two thousand page document that allowed corporations to sue host governments over any laws that might possibly threaten their profits, without regard to national interest. Somehow, nothing was included in the NAFTA, WTO, or other major, U.S. trade and investment deals about exchange rate policy, perhaps the single most important determinant of trade balances (and imbalances), resulting in the loss of millions of jobs due to growing trade deficits with Mexico and China, alone.
The continued opposition of “the American left” to NAFTA and similar deals is easily explained. It’s because the self-styled technocratic center insists on shoving these agreements through the system every chance they get. In 2009 and 2010, in the absolute teeth of the Great Recession (or as DeLong calls it, the Lesser Depression) we got the Korea, Panama and Columbia trade and investment deals shoved down the throats of Congress and “the left.” And it’s well to recall that in 1993, Clinton decided to make NAFTA, rather than health care, the centerpiece of his policy agenda for what became a notably unproductive 8-year term. Despite the well-known failures of past trade and investment deals like NAFTA, the Obama Administration has made negotiating new, job killing agreements like the U.S. Korea Free Trade Agreement Free Trade Agreement and the proposed Trans-Pacific Partnership a centerpiece of its economic policies, based on its claim that such deals will create tens of thousands of “American jobs through increased exports alone.”
NAFTA has had real and significant costs for the vast majority of working Americans, and it never delivered the promised benefits for Mexico. Working Americans and “the left” have very good reasons for opposing such deals and should continue to do so.
EPI and AEI Agree: Cutting Jobless Benefits Did Not Boost Employment
Perhaps Hell has not frozen over, but it appears that someone down there may have leaned on the thermostat. That’s right, the Economic Policy Institute and the American Enterprise Institute are in lock-step agreement on an important fiscal policy matter.
During the Great Recession and its aftermath, the federal government acted to help victims of the severe downturn by funding programs that extended unemployment benefits—to up to 99 weeks in some cases, up from the standard 26 weeks. As the economic recovery continued, weak as it was for many in the working class, many lawmakers on the right began to believe that these extended benefits were a drag on employment—the theory being that government checks reduced the incentive for recipients to find a job, and that cutting off this lifeline would compel unemployed workers to look harder for work and perhaps take jobs they may not have accepted if the benefits had continued. Relying on this premise, Congress allowed the federally-funded Emergency Unemployment Compensation program to lapse last December.
Now, more than seven months later, data are available to test this idea. Coming from perspectives that diverge greatly along the ideological spectrum, scholars at both AEI and EPI have come to the conclusion that this “bootstraps” theory is incorrect—curtailing jobless benefits did not boost employment. Because unemployment benefits are contingent upon the people who receive them proving that they are looking for a job, receiving jobless benefits appears to make recipients at least just as likely, and certainly not less likely, to rejoin the ranks of the employed.