Why Young People Should Care About a Lame Labor Market
I am not as optimistic about my future as my peers tell pollsters they are. Relative to the two previous generations, Millennials have higher levels of student debt, poverty, and unemployment, and lower levels of personal income and wealth. All of this has been covered in depth by the media, but what doesn’t get nearly enough attention given its importance is how poorly the American labor market is performing for my generation.
At EPI, we talk a lot about how weak labor markets hurts workers and their families (something that even The Onion has picked up on). Heidi Shierholz has documented the impact that labor market policies have on workers in various sectors, like domestic workers, and Josh Bivens and I wrote a paper showing how the weak labor market is the main challenge for middle class families in the aftermath of the Great Recession. But it can be hard to understand how the labor market relates to readers my age. With this post, I’m going to try to make the case for why young people should care about what’s going on in the labor market, and why it makes sense for them work to make it better.
A weak labor market hurts the living standards of young people in two immediate ways. First, it disproportionately affects young people’s job opportunities. This is true in good and bad times: unemployment for younger workers is almost always about twice the overall unemployment rate. As of July 2014, the unemployment rate for young workers was 13.6 percent, while unemployment for workers ages 25-54 was 5.2 percent (relative to 10.5 percent and 3.7 percent in 2007, the last time we experienced a “strong” labor market). One of the reasons for this is obvious: young people are inexperienced relative to their older counterparts. In a time of labor market weakness, older, more experienced workers who are newly unemployed will apply to jobs they may be overqualified for, leaving young people to compete with not just their peers but also a larger pool of more experienced candidates. So even while the Great Recession officially ended in 2009, young people are currently facing one extremely competitive labor market.
The Dog That Didn’t Bark, or, Why Wages at the Bottom of the Distribution Were the Only Ones That Didn’t Fall over the past Year
In writing my paper on the most recent wage trends released today, I came across an interesting finding: Wages at the bottom of the wage distribution were the only ones that didn’t fall between the first half of 2013 and first half of 2014. The figure below shows the change in real (inflation-adjusted) wages over this time at different points in the wage distribution. What is obvious from the figure is that wages have fallen for nearly every group. If I showed you the same trends by education, as I do in the paper (see Figure O), you’d see an even starker story: Wages over the past year have fallen for all education groups, including those with college or advanced degrees.
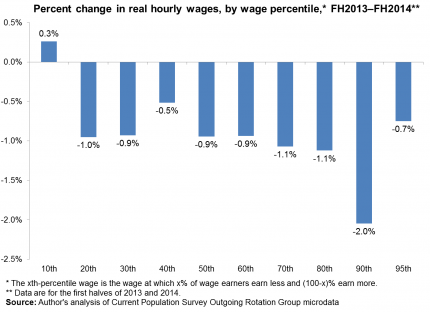
So, why didn’t the 10th percentile wage fall like all others? What is so special about that wage that sits below 90 percent and above 10 percent of workers (i.e., is not generally earned by particularly privileged workers)? Simple—several states raised their minimum wage over that period.
Wages Have Fallen for Most Americans in 2014
Today, we released a report analyzing the most recent reliable data on wages by decile and by educational attainment. These data are illuminating because they look beneath the overall averages presented in the regular statistical series covered by the media. On the one hand, these recent data look quite a bit like the couple of years of data that come before it—but that is still very revealing of what’s going in the economy.
Overall, the trends over the last year—from the first half of 2013 to the first half of 2014—show that real, inflation-adjusted wages fell up and down the entire wage scale, with one revealing notable exception. The recovery has not been completely jobless for a while now, but it does continue to be pretty much wage-less, or at least wage-growth-less.
Let’s start at the top of the wage distribution: those workers with the most education and the highest wages. Over the last year, real wages at the top of the wage distribution fell, by 2.0 percent at the 90th percentile and 0.7 percent at the 95th percentile. Real wages also fell for workers with a 4-year college degree, and even for those workers with an advanced degree. This is important in particular because it sends a clear message to the Federal Reserve Board. If even these groups of highly educated workers facing the lowest unemployment are seeing outright wage declines, there is clearly lots of slack left in the American labor market, and policymakers—particularly the Federal Reserve—should not try to slow the recovery down in an effort to keep wage and price inflation in check: they’re both already firmly in check even for the most privileged workers.
Job Growth in the Great Recession Has Not Been Equal Between Men and Women
While many strides have been made in the women’s equality movement, job growth among women and men in the aftermath of the Great Recession is not one. The solid lines in the figure below show job loss during and after the Great Recession by gender. Men lost far more jobs than women did in the Great Recession—over 6.0 million jobs, or 8.5 percent of their total December 2007 employment, compared to women who lost 2.7 million jobs, or 3.5 percent. Since the economy started regaining jobs, however, the gender dynamic in job growth has reversed—between February 2010 and the June 2014, men gained 5.5 million while women gained 3.6 million jobs.
How did men both lose and then gain more jobs than women? A lot can be explained by the industries men and women were in at the time of the Great Recession—men were in industries that would sustain the most dramatic job loss while women were concentrated in industries with less job loss. The industries with the largest overall job losses—manufacturing and construction—also employed a very large share of men. Meanwhile, the industries that employed the greatest shares of women in 2007—health care and state and local government—were not as hard-hit. However, men have gained more jobs than women because they’ve had stronger job growth within almost every industry. Women experienced a smaller share of net gains between 2007 and 2014 in 10 out of the 16 major industries: manufacturing, whole sale trade, retail trade, professional and business and health care to name a few. (To see how men and women fared in each of the 16 major industries, see my blog post in which I update the distribution of workers across industry by gender during and after the Great Recession.)
A Brief but Sad History of Selected Corporate Inversions
Earlier this week, we were greeted with the news that Burger King, a U.S. fast-food giant, is in talks to merge with Tim Hortons, a much smaller Canadian fast-food chain, and become a Canadian firm. This proposed deal is interesting on many levels. First, it is another example of a corporate inversion in which, to use Edward Kleinbard’s description, a “foreign minnow swallows a domestic whale.”
Second and more importantly, this is a corporate inversion involving a large U.S. corporation and a much smaller foreign corporation that was once a U.S. corporation. Yes, you read that correctly: Tim Hortons was a U.S. corporation prior to its inversion to Canada in 2009. Though to be fair, Tim Hortons started as a Canadian company—it was founded in Hamilton, Ontario in 1964. Wendy’s restaurant chain purchased Tim Hortons in 1995 and then spun-off the company in 2006. Tim Hortons inverted to Canada in 2009 arguing that they had substantial business activity in Canada.
Another Day, Another Corporate Inversion
In looking to merge with Canadian coffee-and-doughnuts icon Tim Hortons, Burger King is just the latest American multinational to buy a smaller foreign company and reincorporate abroad, lowering its tax bill in the process. This maneuver, called a “corporate inversion,” has picked up steam this year as Congress has stood idly by, twiddling its thumbs.
There is something unseemly about corporate inversions—that American companies would reap the benefits of American infrastructure, labor, customers, and local and federal tax incentives, and then move—just on paper—abroad, just to help their bottom lines. Executives of these now “foreign,” inverted companies don’t have to move and the companies can remain listed on American stock exchanges, but some (perfectly-legal) paper shuffling allows them to escape paying U.S. taxes. And while President Obama has appealed to corporations’ sense of “economic patriotism,” the companies—despite recent Supreme Court decisions—are not people; they don’t have emotions separate from their desire to maximize profits.
While both parties profess to disdain the practice of inversions, they disagree on what to do about them. Democrats have taken a sensible approach, writing bills that would prohibit inversions unless 50 percent of the value of the stock of the newly-merged company were held by foreigners (which makes a lot of intuitive sense), up from the current 20 percent as mandated by the most recent anti-inversion legislation, signed into law by George W. Bush. Other proposals would limit the potential benefits of corporate inversions, for example by withholding federal contracts from inverted corporations or by making it harder for a newly-foreign parent company to transfer loads of debt to its now American subsidiary and then write off the interest paid on that debt. (The Obama administration is looking to see if it can implement rule changes like this without Congress’s approval, but worries remain about whether such new rules would survive the inevitable legal challenges.)
Back to School: A Useful Guide for Parents and Policymakers to Use School Quality Rankings
The Wallethub state school quality rankings that were released earlier this month add to a growing list of such guides. They join those of the Education Law Center, which has ranked state school systems since 2011 using a four-part funding equity model, Students First’s state report cards, and the Brookings Institution Brown Center’s Education Choice and Competition rankings of large urban districts. There are many others, but these four illustrate some of the diversity in both approaches to ranking schools and types of institutions that rank them.
All four suggest to parents and policymakers that their system identifies the highest quality schools. Yet they produce a very disparate set of “best” and “worst” states (and districts). Two of Wallethub’s top three—New Jersey and Massachusetts—are among two of the the three states that Education Law Center also ranks highest: New Jersey, Massachusetts, and Connecticut. In contrast, two of Students First’s top-ranked three, Louisiana and Florida, are among the lowest on Education Law Center’s sufficiency ranking. The Brown Center gives top billing to the New Orleans’ Recovery School District, New York City, and Washington, DC, and Students First also gives DC high marks, while Wallethub has it dead last, behind Mississippi. And Wallethub ranks Louisiana, Students First’s top-ranked state, 48th of 51.
As the new school year refocuses our attention on education and school quality, what are we to make of these conflicting numbers? Can we use the rankings to help us make good decisions, whether as parents or policymakers?
The Obama Administration Moves to Protect U.S. Steel Industry from Unfair Trade Practices
Earlier this year, we showed that an increase in illegal steel dumping was putting up to half a million U.S. jobs at risk, in a study I co-authored with the law firm of Stewart and Stewart. On Friday, the U.S. International Trade Commission (USITC) determined by a vote of 5-0 that companies from South Korea, along with five other countries (India, Turkey, Ukraine, Vietnam, and Taiwan) are dumping Oil Country Tubular Goods (OCTG) into the U.S. steel market. Countervailing duties will also be assessed on OCTG imports from Turkey and India. OCTG is a high-value steel product used in the rapidly growing U.S. oil and gas fracking industry. U.S. imports of OCTG products from the subject countries more than doubled between 2010 and 2013. South Korean imports, which represent more than half of all U.S. OCTG imports, were being shipped to the United States at prices far below fair value.
The USITC vote follows on the heels of a decision by the Commerce Department that it would impose punitive tariffs on manufacturers of OCTG from Korea and the other countries involved in this case. As I noted last month, Commerce’s decision (today endorsed by the USITC) to assess duties on OCTG imports from Korea and other countries is a victory for steel workers, U.S. steel producers, and the millions of people whose jobs depend on the U.S. steel industry.
In the run-up to the decision, U.S. steelworkers mounted a “nationwide call to action” to “ensure that our trade laws are fully enforced.” This campaign featured rallies in six of the major steel-producing states, which were supported by bipartisan letters signed by more than 150 members of the U.S. House of Representatives and by 57 members of the U.S. Senate. As Steelworkers President Leo Girard pointed out, this national campaign “should not be necessary to ensure that our trade laws are enforced.” U.S. officials should enforce U.S. fair trade laws to the fullest extent allowable under U.S. and international law. And the time has come for a complete reassessment of U.S. trade laws to close loopholes and ensure that the law is promptly and effectively enforced to the full extent intended by Congress and the president.
A Salute to Jim Jeffords, a True Vermont Progressive
I was saddened to learn of the death of Sen. Jim Jeffords of Vermont this week. He was the rare politician who combined intelligence, humility, and a sense of humor, with a deep love for his state and his country. Like Sen. Paul Wellstone, Jeffords never held himself above the congressional staff who worked for him and around him, and he certainly didn’t hold himself above the people he represented, despite his Harvard and Yale degrees and his elevated position, which ultimately included service as chairman of the Senate Committee on Health, Education, Labor and Pensions and the Committee on Environment and Public Works.
When I first met Jeffords in 1982, he was a senior Republican on the House Education and Labor Committee, already exercising an independent streak by opposing Ronald Reagan’s efforts to eliminate any role for the federal government in employment and training programs. He supported the Job Training Partnership Act, and got involved in the bill’s minutiae, sitting late at night with mostly Democratic staffers as the formulas for distributing funds to the states and local entities were worked out. By pushing to give greater weight to factors like poverty, unemployment, long-term unemployment, or total population in the formulas, a state like Vermont could see its funding change dramatically, and Jeffords made sure the staff assigned to negotiate and draft the bill pushed the right buttons for his state. He was the only member of Congress in the room.
Broadening Agreement That Job Polarization Wasn’t Present in the United States In 2000s
A common but erroneous theme in the media about recent labor market trends is that technology (the robots!) threatens job growth and is the cause of wage stagnation and inequality. Politicians, policymakers, and pundits echo this as well. These insights come from research on the “job polarization hypotheses”—the claim that computerization leads to the “simultaneous growth of high-education, high-wage and low-education, low-wages jobs at the expense of middle-wage, middle education jobs” and, correspondingly, to wage polarization. It is noteworthy, therefore, that MIT Professor David Autor, the leading intellectual architect of the job polarization hypothesis, has presented a paper at the Federal Reserve Bank of Kansas City’s economic policy symposium in Jackson Hole, Wyo., which finds that job polarization did not occur in the 2000s and that, in any case, job polarization is not necessarily connected to wage polarization.
This confirms the findings of others, such as Beaudry, Green, and Sand and my own research with Heidi Shierholz and John Schmitt. One can only applaud Autor for updating his analysis of employment and wage trends, and acknowledging the lack of occupational job polarization in the 2000s and its failure to be able to explain wage trends. One can only hope that the economics commentariat will follow suit and ramp up their exploration of other causes of stagnant and unequal wage growth. Immodestly, I would suggest our recent paper, Raising America’s Pay, as a starting point.
In 2010, Autor wrote the influential paper The Polarization of Job Opportunities in the U.S. Labor Market: Implications for Employment and Earnings for the Center for American Progress and the Hamilton Project. This paper laid out what became the conventional wisdom: “the structure of job opportunities in the United States has sharply polarized over the past two decades, with expanding job opportunities in both high-skill, high-wage occupations and low-skill, low wage occupations, coupled with contracting opportunities in middle-wage, middle-skill white-collar and blue-collar jobs” and “this pattern of employment polarization has a counterpart in wage growth.”