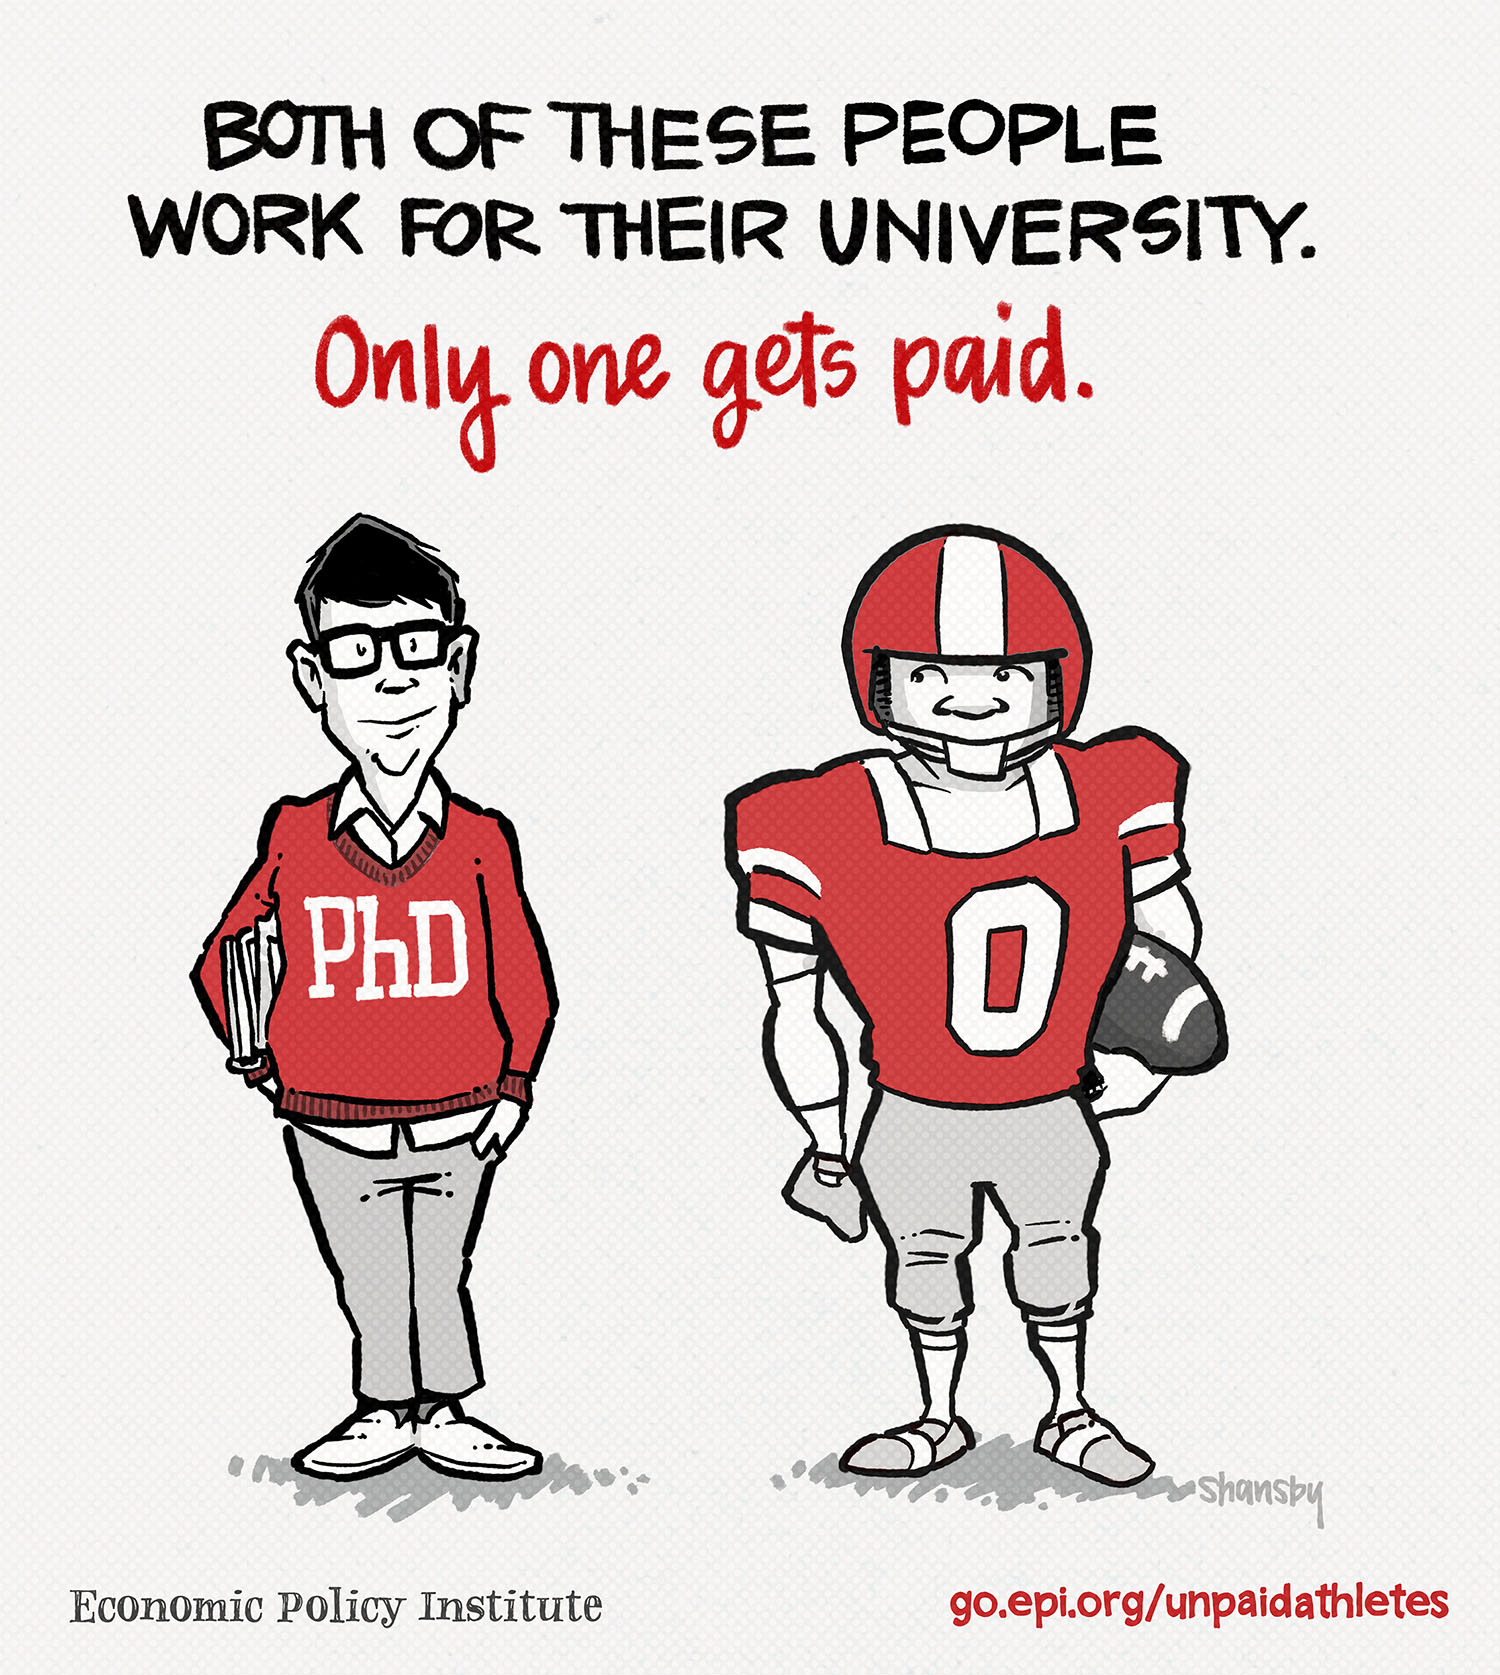
College athletes and Ph.D. students both work for the university, but only one earns a salary
Beginning in January 2021, new rules will go into effect that will allow NCAA student-athletes to profit from the use of their names, images, and likeness. While the details of these new rules will require much deliberation among each NCAA division, one thing will not be considered—salaries for college athletes from the universities.
Why won’t college athletes be paid a salary?
Several reasons are floating around. One reason is the NCAA does not consider college athletes employees of the universities. Another reason is that these players are given a lot of perks. In a recent Los Angeles Times article, Dan Radakovich, athletic director at Clemson University, argued against paying college athletes since they have access to “world-class facilities, world-class coaching, and incredible academic support.”
But there already exists a group of students who are employees of the university, have access to world-class facilities, teaching, and academic support, and no one calls them selfish when they receive their salaries. Who are these students? Ph.D. students.
Wait, are you saying Ph.D. students receive a salary?
Yes, because they work for the university. A large percentage of Ph.D. students are funded via fellowships or assistantships. Funding, which covers tuition and provides a stipend, varies across institutions and doctoral programs due to what can be viewed as “educational hierarchy.” Assistantships require that Ph.D. students’ work anywhere from 20 to 40 hours per week that include duties such as grading, managing labs, or lecturing. Additionally, doctoral students are awarded (or sometimes apply for) money that allows them to attend international or out-of-state conferences to present their research and network with others in their field.
In short, Ph.D. students sign a contract with an institution, agree to work a certain number of hours per week, maintain a certain GPA, and conduct research. In exchange, the university covers their tuition and pays them a salary. What do college football players do? Sign a contract (you may have seen signing day on ESPN), maintain a certain GPA, and kick butt on Saturday, which requires countless hours of practice! Additionally, their success can help recruit up to tens of thousands of students and generate millions of dollars for the institution.
Nearly 7 million workers will start the new year with higher wages
Note: This post was updated to clarify that Delaware’s minimum wage increase took effect on October 1, 2019.
At the start of the new year, minimum wages will have gone up in 22 states, lifting pay for 6.8 million workers across the country.i In total, workers affected by the increases will earn an extra $8.2 billion over the course of 2020 as a result of the changes. The increases range from a $0.10 inflation adjustment in Florida to $1.50 per hour raises in New Mexico and Washington. Affected workers who work year-round will see their annual pay go up between $150 and $1,700, on average, depending on the size of the minimum wage increase in their state.
The map and table below describe the increases in each state. Note that these estimates do not account for changes in local minimum wages separate from state law.ii There are 22 cities and counties with higher minimum wages taking effect on January 1, all of which can be found in EPI’s Minimum Wage Tracker. The estimates also do not include any “indirectly affected workers” making just above the new minimum wage who may receive raises as employers adjust their overall pay scales.
State minimum wage increases will raise pay for nearly 7 million workers on January 1: States with minimum wage increases effective January 1, 2020, by type of increase
| State | Share of workforce directly benefiting | Type of increase | New minimum wage as of Jan. 1, 2020 | Amount of increase | Total workers directly benefiting | Total increase in annual wages | Average increase in annual earnings of year-round workers | |
|---|---|---|---|---|---|---|---|---|
| Alabama | -1 | 0.00% | ||||||
| Connecticut | 0 | 0.00% | ||||||
| Georgia | -1 | 0.00% | ||||||
| Hawaii | 0 | 0.00% | ||||||
| Idaho | -1 | 0.00% | ||||||
| Indiana | -1 | 0.00% | ||||||
| Iowa | -1 | 0.00% | ||||||
| Kansas | -1 | 0.00% | ||||||
| Kentucky | -1 | 0.00% | ||||||
| Louisiana | -1 | 0.00% | ||||||
| Mississippi | -1 | 0.00% | ||||||
| Nebraska | 0 | 0.00% | ||||||
| Nevada | 0 | 0.00% | ||||||
| New Hampshire | -1 | 0.00% | ||||||
| North Carolina | -1 | 0.00% | ||||||
| North Dakota | -1 | 0.00% | ||||||
| Oklahoma | -1 | 0.00% | ||||||
| Oregon | 0 | 0.00% | ||||||
| Pennsylvania | -1 | 0.00% | ||||||
| Rhode Island | 0 | 0.00% | ||||||
| South Carolina | -1 | 0.00% | ||||||
| Tennessee | -1 | 0.00% | ||||||
| Texas | -1 | 0.00% | ||||||
| Utah | -1 | 0.00% | ||||||
| Virginia | -1 | 0.00% | ||||||
| Washington D.C. | 0 | 0.00% | ||||||
| West Virginia | 0 | 0.00% | ||||||
| Wisconsin | -1 | 0.00% | ||||||
| Wyoming | -1 | 0.00% | ||||||
| Ohio | 1 | 1.60% | Inflation adjustment | $ 8.70 | $ 0.15 | 84,000 | $ 12,303,000.00 | $ 150.00 |
| South Dakota | 1 | 1.70% | Inflation adjustment | $ 9.30 | $ 0.20 | 7,300 | $ 1,560,000.00 | $ 220.00 |
| Florida | 1 | 1.90% | Inflation adjustment | $ 8.56 | $ 0.10 | 160,700 | $ 23,766,000.00 | $ 150.00 |
| Montana | 1 | 1.90% | Inflation adjustment | $ 8.65 | $ 0.15 | 8,900 | $ 1,588,000.00 | $ 180.00 |
| Minnesota | 1 | 2.40% | Inflation adjustment | $ 10.00 | $ 0.14 | 68,100 | $ 11,030,000.00 | $ 162.00 |
| New Mexico | 2 | 2.70% | Legislation | $ 9.00 | $ 1.50 | 22,900 | $ 20,736,000.00 | $ 900.00 |
| Alaska | 1 | 3.00% | Inflation adjustment | $ 10.19 | $ 0.30 | 10,500 | $ 5,348,000.00 | $ 510.00 |
| Illinois | 2 | 3.30% | Legislation | $ 9.25 | $ 1.00 | 192,900 | $ 173,533,000.00 | $ 900.00 |
| Michigan | 2 | 3.40% | Legislation | $ 9.65 | $ 0.20 | 147,000 | $ 32,907,000.00 | $ 220.00 |
| Delaware | 2 | 4.00% | Legislation | $ 9.25 | $ 0.50 | 17,200 | $ 10,811,000.00 | $ 630.00 |
| New York | 2 | 4.00% | Legislation | $ 11.80 | $ 0.70 | 411,700 | $ 399,246,000.00 | $ 970.00 |
| Vermont | 1 | 5.20% | Inflation adjustment | $ 10.96 | $ 0.19 | 16,200 | $ 3,932,000.00 | $ 240.00 |
| Missouri | 3 | 5.40% | Ballot measure | $ 9.45 | $ 0.85 | 153,600 | $ 123,505,000.00 | $ 800.00 |
| Maryland | 2 | 7.60% | Legislation | $ 11.00 | $ 0.90 | 204,300 | $ 216,530,000.00 | $ 1,060.00 |
| Arkansas | 3 | 11.00% | Ballot measure | $ 10.00 | $ 0.75 | 119,300 | $ 113,142,000.00 | $ 950.00 |
| Washington | 3 | 11.60% | Ballot measure | $ 13.50 | $ 1.50 | 386,000 | $ 655,972,000.00 | $ 1,700.00 |
| New Jersey | 2 | 11.70% | Legislation | $ 11.00 | $ 1.00 | 460,400 | $ 480,308,000.00 | $ 1,040.00 |
| Massachusetts | 2 | 12.00% | Legislation | $ 12.75 | $ 0.75 | 420,600 | $ 409,981,000.00 | $ 970.00 |
| Colorado | 3 | 12.10% | Ballot measure | $ 12.00 | $ 0.90 | 318,400 | $ 382,354,000.00 | $ 1,200.00 |
| California | 2 | 16.90% | Legislation | $ 13.00 | $ 1.00 | 2,950,200 | $ 4,376,241,000.00 | $ 1,480.00 |
| Maine | 3 | 16.90% | Ballot measure | $ 12.00 | $ 1.00 | 102,900 | $ 130,250,000.00 | $ 1,270.00 |
| Arizona | 3 | 17.70% | Ballot measure | $ 12.00 | $ 1.00 | 511,900 | $ 653,915,000.00 | $ 1,300.00 |
Notes: *The New York minimum wage changes take effect on December 31, 2019. Delaware's minimum wage increase took effect on October 1. “Legislation” indicates that the new rate was established by the legislature. “Ballot measure” indicates the new rate was set by a ballot initiative passed by voters. “Inflation adjustment” indicates that the new rate was established by a formula, reflecting the change in prices over the preceding year.
Directly affected workers will see their wages rise because the new minimum wage rate exceeds their current hourly pay. This does not include additional workers who may receive a wage increase through “spillover” effects, as employers adjust overall pay scales.
Estimates for New York reflect changes in the minimum wage applicable to upstate New York ($11.80) and Nassua, Suffolk, and Westchester counties ($13.00). New York City's minimum wage reached $15 at the end of 2018 and there are no further increases scheduled.
Population growth between the data period and January 2020 estimated using state-specific projections for growth in the total population or the population ages 15—69, where available. Nominal wage growth between the data period (2017) and January 2020 estimated using the 3-year average of nominal wage growth of the bottom 20 percent of wage earners in each state from 2015 to 2018. A full methodology is available in Minimum Wage Simulation Model Technical Methodology.
Source: Economic Policy Institute Minimum Wage Simulation Model using data from the Census Bureau, Bureau of Labor Statistics, and Congressional Budget Office. See Minimum Wage Simulation Model technical methodology [https://www.epi.org/publication/minimum-wage-simulation-model-technical-methodology/].
In seven states, the changes are the result of automatic annual inflation adjustments. Alaska, Florida, Minnesota, Montana, Ohio, South Dakota, and Vermont all have provisions in their state minimum wage laws that require the wage be adjusted annually to reflect changes in prices over the preceding year. Doing so ensures that the minimum wage never declines in purchasing power, and workers paid the minimum wage can afford the same amount of goods and services year after year. 10 other states and the District of Columbia have enacted similar automatic adjustment provisions in their minimum wage laws that will begin after their minimum wages reach a higher statutory level in the coming years.
The increases in nine states—California, Delaware, Illinois, Maryland, Massachusetts, Michigan, New Jersey, New Mexico, and New York—are the result of legislation passed by state lawmakers to raise their state’s wage floors. Lawmakers in six of these states—California, Illinois, Maryland, Massachusetts, New Jersey, and New York—enacted legislation that will eventually bring their state minimum wages to $15 an hour. For 2020, minimum wages in these states will range between $11.00 and $13.00.
In six states—Arizona, Arkansas, Colorado, Maine, Missouri, and Washington—the January 1 raises result from ballot measures passed by the state’s voters. In the last several election cycles, voters have increasingly passed higher minimum wages, often in the face of inaction by their state legislatures. In fact, voters in Missouri passed a higher state minimum wage at the ballot box after state lawmakers nullified city minimum wage ordinances that had been enacted by local governments in Kansas City and St. Louis.Read more
Top 1.0% of earners see wages up 157.8% since 1979
Newly available wage data for 2018 show that annual wages for the top 1.0% were nearly flat (up 0.2%) while wages for the bottom 90% rose an above-average 1.4%. Still, the top 1.0% has done far better in the 2009–18 recovery (their wages rose 19.2%) than did those in the bottom 90%, whose wages rose only 6.8%. Over the last four decades since 1979, the top 1.0% saw their wages grow by 157.8% and those in the top 0.1% had wages grow more than twice as fast, up 340.7%. In contrast those in the bottom 90% had annual wages grow by 23.9% from 1979 to 2018. This disparity in wage growth reflects a sharp long-term rise in the share of total wages earned by those in the top 1.0% and 0.1%.
These are the results of EPI’s updated series on wages by earning group, which is developed from published Social Security Administration data and updates the wage series from 1947–2004 originally published by Kopczuk, Saez and Song (2010). These data, unlike the usual source of our other wage analyses (the Current Population Survey) allow us to estimate wage trends for the top 1.0% and top 0.1% of earners, as well as those for the bottom 90% and other categories among the top 10% of earners. These data are not top-coded, meaning the underlying earnings reported are actual earnings and not “capped” or “top-coded” for confidentiality.
Cumulative percent change in real annual wages, by wage group, 1979–2018
| Year | Bottom 90% | 90th–95th | 95th–99th | Top 1% |
|---|---|---|---|---|
| 1979 | 0.0% | 0.0% | 0.0% | 0.0% |
| 1980 | -2.2% | -1.3% | -0.2% | 3.4% |
| 1981 | -2.6% | -1.1% | -0.1% | 3.1% |
| 1982 | -3.9% | -0.9% | 2.2% | 9.5% |
| 1983 | -3.7% | 0.7% | 3.6% | 13.6% |
| 1984 | -1.8% | 2.5% | 6.0% | 20.7% |
| 1985 | -1.0% | 4.0% | 8.1% | 23.0% |
| 1986 | 1.1% | 6.4% | 12.5% | 32.6% |
| 1987 | 2.1% | 7.4% | 15.0% | 53.5% |
| 1988 | 2.2% | 8.2% | 18.4% | 68.7% |
| 1989 | 1.8% | 8.1% | 18.2% | 63.3% |
| 1990 | 1.1% | 7.1% | 16.5% | 64.8% |
| 1991 | 0.0% | 6.9% | 15.5% | 53.6% |
| 1992 | 1.5% | 9.0% | 19.2% | 74.3% |
| 1993 | 0.9% | 9.2% | 20.6% | 67.9% |
| 1994 | 2.0% | 11.2% | 21.0% | 63.4% |
| 1995 | 2.8% | 12.2% | 24.1% | 70.2% |
| 1996 | 4.1% | 13.6% | 27.0% | 79.0% |
| 1997 | 7.0% | 16.9% | 32.3% | 100.6% |
| 1998 | 11.0% | 21.3% | 38.2% | 113.1% |
| 1999 | 13.2% | 25.0% | 42.9% | 129.7% |
| 2000 | 15.3% | 26.8% | 48.0% | 144.8% |
| 2001 | 15.7% | 29.0% | 46.4% | 130.4% |
| 2002 | 15.6% | 29.0% | 43.2% | 109.3% |
| 2003 | 15.7% | 30.3% | 44.9% | 113.9% |
| 2004 | 15.6% | 30.8% | 47.1% | 127.2% |
| 2005 | 15.0% | 30.8% | 48.6% | 135.3% |
| 2006 | 15.7% | 32.5% | 52.1% | 143.4% |
| 2007 | 16.6625450273242% | 34.0650819079098% | 55.3586221137521% | 156.174314731946% |
| 2008 | 16.0% | 34.2% | 53.8% | 137.5% |
| 2009 | 16.0% | 35.3% | 53.5% | 116.2% |
| 2010 | 15.2% | 35.7% | 55.7% | 130.8% |
| 2011 | 14.5% | 36.2% | 56.9% | 134.0% |
| 2012 | 14.6% | 36.3% | 58.3% | 148.3% |
| 2013 | 15.1% | 37.1% | 59.4% | 137.5% |
| 2014 | 16.6% | 38.7% | 62.3% | 149.0% |
| 2015 | 20.5% | 43.1% | 67.9% | 156.2% |
| 2016 | 21.0% | 43.5% | 68.1% | 148.1% |
| 2017 | 22.2% | 44.2% | 69.3% | 157.3% |
| 2018 | 23.9% | 45.7% | 71.3% | 157.8% |
Source: EPI analysis of Kopczuk, Saez, and Song (2010, Table A3) and Social Security Administration wage statistics
As Figure A shows, the top 1.0% of earners are now paid 157.8% more than they were in 1979. Even more impressive is that those in the top 0.1% had more than double that wage growth, up 340.7% since 1979 (Table 1). In contrast, wages for the bottom 90% only grew 23.9% in that time. Since the Great Recession, the bottom 90%, in contrast, experienced very modest wage growth, with annual wages—reflecting growing annual hours as well as higher hourly wages—up just 6.8% from 2009 to 2018. In contrast, the wages of the top 0.1% grew 19.2% during those nine years.Read more
Three Republican-appointed white men are now deciding whether you have rights on the job
Yesterday marked the end of Democratic National Labor Relations Board (NLRB) Member Lauren McFerran’s term. McFerran ended her term offering the lone dissenting voice in the Trump board’s efforts to slow down union elections to give employers more time to campaign against the union, give employers the ability to make unilateral changes without bargaining with their workers’ union, weaken remedies when employers break the law, and more.
McFerran is the former Chief Labor Counsel for the Senate Committee on Health, Education, Labor, and Pensions (HELP Committee) and is widely respected by both labor and management. Her departure leaves a second open seat on the board that the Trump administration is tasked with filling. However, the Trump administration has not yet acted to nominate McFerran for a second term, nor has it nominated a Democrat to fill the other vacant Democratic seat that has been open since August 2018. The failure of the Trump administration to act is not for lack of a qualified nominee with widespread support. Former deputy general counsel and longtime NLRB career attorney Jennifer Abruzzo has reportedly been under consideration.
As a result, the NLRB has only Republican appointees for the first time in its 85-year history, and the three Republicans are all white men—two lawyers who represented corporations before coming to the NLRB, and one former Republican congressional staffer. There is no Democratic appointee to offer alternative views on workers’ rights under the National Labor Relations Act (NLRA), or to issue dissenting opinions when the Trump board goes off track. And there are no women or people of color participating in these decisions, even though women and people of color make up the majority of workers.
EPI previously reported on the unprecedented rollback of workers’ rights happening at the hands of these three NLRB appointees. The U.S. Chamber of Commerce—the nation’s largest business lobby—is 10 for 10 in winning action on its top 10 “wish list” for the Trump board. Unfortunately, things are likely to get worse, not better. With no Democratic appointee there to provide an alternative or dissenting viewpoint on the Trump board’s actions, we are likely to see a continued rollback of workers’ rights under this bedrock statute that, after all, is supposed to protect workers’ rights.
On its second anniversary, the TCJA has cut taxes for corporations, but nothing has trickled down
It’s been two years since Republicans passed their Tax Cuts and Jobs Act (TCJA), enough time for its effects to have come into full view. As we lay out in a report released today with the Center for Popular Democracy, the economic data that has come in since its passage has not been kind to the argument of the TCJA’s proponents.
The centerpiece of the TCJA was a large cut in the corporate tax rate. Supporters of the TCJA made the supply-side argument that higher corporate profits would juice investment, which would eventually trickle down to faster productivity growth that would mechanically boost workers’ wages. The theory behind this relied on a long chain of economic events occurring, and it was clear from the very beginning that there was little reason to trust a single link in the chain.
Despite some disingenuous and cynical arguments surrounding wages and bonuses, if the TCJA is to work as its supporters claimed, then the first thing we would see is a substantial uptick in investment. After two years, there is no evidence of any investment boom. Instead, investment growth followed along its pre-TCJA trend for a couple of quarters and then cratered. Year-over-year investment growth has sunk from 5.4% at the time of the TCJA’s passage to just 1.3% in the most recent quarter.
More evidence the Trump tax cuts aren’t working as advertised: Change in real, nonresidential fixed investment shows no investment boom
| Years | Real, nonresidential fixed investment |
|---|---|
| 2003-Q1 | -2.3% |
| 2003-Q2 | 1.6% |
| 2003-Q3 | 4.0% |
| 2003-Q4 | 6.8% |
| 2004-Q1 | 5.2% |
| 2004-Q2 | 4.9% |
| 2004-Q3 | 5.7% |
| 2004-Q4 | 6.5% |
| 2005-Q1 | 9.2% |
| 2005-Q2 | 8.2% |
| 2005-Q3 | 7.4% |
| 2005-Q4 | 6.1% |
| 2006-Q1 | 8.0% |
| 2006-Q2 | 8.2% |
| 2006-Q3 | 7.8% |
| 2006-Q4 | 8.1% |
| 2007-Q1 | 6.5% |
| 2007-Q2 | 7.0% |
| 2007-Q3 | 6.8% |
| 2007-Q4 | 7.3% |
| 2008-Q1 | 5.8% |
| 2008-Q2 | 3.8% |
| 2008-Q3 | 0.2% |
| 2008-Q4 | -7.0% |
| 2009-Q1 | -14.4% |
| 2009-Q2 | -17.1% |
| 2009-Q3 | -16.1% |
| 2009-Q4 | -10.3% |
| 2010-Q1 | -2.3% |
| 2010-Q2 | 4.1% |
| 2010-Q3 | 7.5% |
| 2010-Q4 | 8.9% |
| 2011-Q1 | 8.0% |
| 2011-Q2 | 7.3% |
| 2011-Q3 | 9.3% |
| 2011-Q4 | 10.0% |
| 2012-Q1 | 12.9% |
| 2012-Q2 | 12.6% |
| 2012-Q3 | 7.2% |
| 2012-Q4 | 5.6% |
| 2013-Q1 | 4.3% |
| 2013-Q2 | 2.3% |
| 2013-Q3 | 4.4% |
| 2013-Q4 | 5.4% |
| 2014-Q1 | 5.5% |
| 2014-Q2 | 8.1% |
| 2014-Q3 | 8.4% |
| 2014-Q4 | 6.9% |
| 2015-Q1 | 5.3% |
| 2015-Q2 | 3.0% |
| 2015-Q3 | 1.3% |
| 2015-Q4 | -0.1% |
| 2016-Q1 | -0.3% |
| 2016-Q2 | -0.1% |
| 2016-Q3 | 0.7% |
| 2016-Q4 | 1.8% |
| 2017-Q1 | 3.6% |
| 2017-Q2 | 3.6% |
| 2017-Q3 | 2.9% |
| 2017-Q4 | 4.8% |
| 2018-Q1 | 6.4% |
| 2018-Q2 | 7.4% |
| 2018-Q3 | 7.5% |
| 2018-Q4 | 6.5% |
| 2019-Q1 | 4.5% |
| 2019-Q2 | 2.9% |
| 2019-Q3 | 2.7% |
| 2019-Q4 | 1.4% |
| 2020-Q1 | -1.3% |
| 2020-Q2 | -8.9% |
Note: Chart shows year-over-year change in real, nonresidential fixed investment from 2003Q1 to 2020Q2.
Source: Adapted from Figure A in Hunter Blair, "The Tax Cuts and Jobs Act Isn’t Working and There’s No Reason to Think That Will Change," Working Economics (Economic Policy Institute blog), October 31, 2019.
Source: Adapted from Figure A in Hunter Blair, The Tax Cuts and Jobs Act Isn’t Working and There’s No Reason to Think That Will Change, Economic Policy Institute, October 2019. Data are from EPI analysis of data in Table 1.1.6 from the National Income and Product Accounts (NIPA) from the Bureau of Economic Analysis (BEA).
To be blunt, this means that the $4,000 annual boost to average incomes that the White House Council of Economic Advisers promised to working families because of the TCJA did not—and will not—happen. While it’s been worse-than-advertised for working families, the TCJA has been an even bigger boon to large corporations and rich households. In fact, corporate tax revenues have come in even lower than the Congressional Budget Office originally projected, allowing corporations and their shareholders to make out like bandits.
The Farm Workforce Modernization Act allows employers to hire migrant farmworkers with H-2A temporary visas for year-round jobs: Impacts are unknown and other wage-setting formulas should be considered
My last blog post described in detail how the Farm Workforce Modernization Act (FWMA)—a bipartisan piece of legislation in the House of Representatives that would legalize unauthorized immigrant farmworkers, make major reforms and expansions to the H-2A temporary work visa program, and require farm employers to use E-Verify—included an updated H-2A wage rule that could lower wages for migrant farmworkers. I also called on the House of Representatives to further assess the impacts of that the FWMA could have on the farm labor market by holding public hearings in the relevant committees of jurisdiction with expert testimony before voting on the bill. One of the other major provisions in the bill that also desperately needs a closer look is the FWMA’s proposal to allow H-2A jobs—which currently must only offer temporary or seasonal work—to become eligible for year-round agricultural occupations.
A look at annual average employment in in the Bureau of Labor Statistics’ (BLS) Quarterly Census of Employment and Wages (QCEW) data set shows there were just over 419,000 year-round jobs in agriculture, mostly in greenhouse and nursery production (155,000) and animal production and aquaculture (264,000), which represent the major year-round occupational categories in agriculture. Farm employers have been clamoring for years for Congress to allow them to hire temporary H-2A workers for many of these 419,000 permanent, year-round jobs, especially on dairies. Since they haven’t had the requisite support to pass legislation that would accomplish this, members of Congress have attempted multiple times to circumvent the regular legislative process by pushing to make the change through legislative riders on annual omnibus appropriations bills.
The FWMA contains provisions to make H-2A year round: For the first three years after enactment, 20,000 three-year H-2A visas per year would be made available for year-round agricultural jobs—meaning 60,000 after three years—with half allocated for the dairy industry. Although the maximum allowed number of year-round H-2A jobs seems relatively small at first, the number could rise rapidly—in years four through 10, the cap could increase by 12.5% per year—and after the tenth year, the cap could be eliminated.
Looking for evidence of wage-led productivity growth: EPI Macroeconomics Newsletter
While unemployment rates are sitting at their lowest levels in decades, wage growth (adjusted for inflation) remains slower than in previous periods of comparably low unemployment. Part of the reason why wage growth remains subdued is that productivity growth has been generally weak since the Great Recession ended. This week’s newsletter provides some guidance on a key question for macroeconomic policymakers like the Federal Reserve: do we need to take this slow rate of productivity growth as a given, or can we nudge productivity upward by allowing unemployment to sink even lower for longer?
Specifically, I address the widespread speculation about the possibility of “wage-led productivity growth”—the hypothesis that tight labor markets that push up labor costs lead firms to invest more in labor-saving equipment and practices. Some suggestive evidence of this wage-led productivity growth has been shown in patterns of macroeconomic data. This newsletter provides some more suggestive evidence from patterns of productivity growth broadly but also across a set of very detailed industries when the labor share of industry income rises and falls. Here are the key findings:
- At the aggregate level, a rise in the labor share of corporate-sector income is associated with a small but significant rise in the pace of average productivity growth over the subsequent two years.
- At detailed industrial levels (looking at 124 industries mostly in manufacturing), this relationship is even stronger: a 1 percentage-point rise in the labor share of industry income is associated with a 0.1 percentage-point increase in the average pace of productivity growth over the subsequent two years.
- These relationships between labor share of income and productivity growth are consistent with a scenario in which firms try harder to make labor-saving investments and organizational changes when labor becomes scarcer and the need to pay higher wages threatens to pinch profits. If the labor share of corporate-sector income rose from today’s 78% to the 82% that characterized the tight labor markets of 2000, this would imply a boost to productivity of roughly 0.4 percentage points—an amount that would cut almost in half the gap between the productivity growth in recent years and the productivity growth of the late 1990s.
These results are obviously suggestive, not dispositive. The key challenge to testing the causal link that runs from higher pressure labor markets to increased effort by firms to find and adopt labor-saving practices and investments is finding truly exogenous changes in labor market tightness. This search for exogenous changes in the cost pressures firms face should be a prime preoccupation for macroeconomic policymakers in the near future. In the rest of this newsletter, we’ll describe our findings in a bit more detail and discuss their potential implications.Read more
House vote imminent on the bipartisan Farm Workforce Modernization Act—which would lower wages for migrant farmworkers: Hearings and assessments of impacts still needed
On October 30, Representatives Zoe Lofgren (D-Cal.) and Dan Newhouse (R-Wash.), along with dozens of other bipartisan cosponsors, introduced the Farm Workforce Modernization Act (FWMA), a compromise bill negotiated between representatives of agribusiness, farmworker advocates, and unions that would legalize unauthorized immigrant farmworkers, make major reforms and expansions to the H-2A temporary work visa program, and require farm employers to use E-Verify, an electronic employment verification system, to verify whether newly hired workers are authorized to be employed in the United States. The FWMA could legalize hundreds of thousands of unauthorized farmworkers while restructuring the landscape for farm employment. The House of Representatives looks set to vote on the FWMA as early as this week.
The FWMA would solve an important farm labor issue—perhaps the most important issue—legalizing unauthorized farm workers and their families. But it would also change the rules of a problematic temporary work visa program, H-2A, where migrant workers are indentured to their employers, often abused and exploited in the fields, paid low wages and robbed of their wages, sometimes live in substandard housing, and have at times been victims of human trafficking.
The H-2A rule changes in the FWMA would expand the H-2A program to year-round occupations, prohibit wage growth that might otherwise occur in the free market, and codify into law most of a new H-2A wage regulation that was recently put into place by the Trump administration—which is geared towards lowering the wages of most migrant workers in the H-2A program—and which many worker advocates opposed publicly. These provisions should raise concerns about the impact of the FWMA on the H-2A program and the future farm labor force but have not yet been explored in any congressional hearing focusing on the FWMA or through the publication of any government reports, or even credible research by non-governmental organizations.
Considering the large and emerging role of H-2A in farm labor, perhaps the single biggest question about the FWMA from a labor standards perspective is: what will happen to H-2A wage rates under the bill? The FWMA updates and codifies a new H-2A wage rule—known as the Adverse Effect Wage Rate or AEWR. In the absence of any existing credible analysis of the FWMA, I offer some comments below outlining my concerns with some of the H-2A wage provisions in the bill. In order to understand its possible impact however, a brief discussion of the current AEWR and the recently proposed Trump H-2A wage rule is needed because the FWMA mostly incorporates the proposed Trump H-2A wage rule.Read more
What to watch on jobs day: Concerning slowdown in job growth and weakening wage growth
As we approach the end of 2019, it’s important to keep the long-run perspective on economic health in mind, but also investigate new trends that have emerged in the last several months that need to be closely monitored. Two concerning trends are the slowdown in nominal wage growth as well as the slowdown in payroll employment growth.
Let’s start with payroll employment growth. On its face, the pace of job growth in 2019 hasn’t been particularly troubling. The economy continues to move in the right direction—though at a slightly slower pace than the last couple of years—soaking up sidelined workers as the unemployment rate remains at historically low levels. But, when you factor in the preliminary benchmark revisions—which showed a half million fewer jobs created between April 2018 and March 2019—the data indicate weaker employment growth this year than originally reported. The final benchmark revisions won’t be released until the January 2020 employment numbers are released in February, but the preliminary release is troubling. And large downward revisions are sometimes associated with early signs of a recession because it means the Bureau of Labor Statistics (BLS)’s model for predicting the births and deaths of firms is off, often accompanied by a turning point in the economy. These revisions don’t tell us a recession is necessary on the immediate horizon, but they are certainly something to keep in mind as the year winds down.
While the topline numbers are important to track, it’s also important to look under the hood. Manufacturing employment, for instance, has exhibited a notable slowdown in employment growth this year. The figure below shows the month-to-month change in manufacturing employment over the last two years with two important modifications. First, I’m using a three-month moving average to smooth the volatility in the series. Second, I’m removing the effect of the 46,000 striking GM workers that depressed the October numbers.
Manufacturing employment growth tapers off: Manufacturing monthly employment growth, in thousands, three month moving average, October 2017–October 2019
| Date | Three month moving average |
|---|---|
| 2017-10-01 | 23.3 |
| 2017-11-01 | 19.3 |
| 2017-12-01 | 26.0 |
| 2018-01-01 | 24.7 |
| 2018-02-01 | 25.0 |
| 2018-03-01 | 22.3 |
| 2018-04-01 | 24.3 |
| 2018-05-01 | 21.0 |
| 2018-06-01 | 25.0 |
| 2018-07-01 | 24.3 |
| 2018-08-01 | 20.0 |
| 2018-09-01 | 15.3 |
| 2018-10-01 | 18.3 |
| 2018-11-01 | 24.7 |
| 2018-12-01 | 25.3 |
| 2019-01-01 | 21.3 |
| 2019-02-01 | 15.0 |
| 2019-03-01 | 7.3 |
| 2019-04-01 | 2.7 |
| 2019-05-01 | 0.7 |
| 2019-06-01 | 5.0 |
| 2019-07-01 | 5.3 |
| 2019-08-01 | 5.3 |
| 2019-09-01 | 0.3 |
| 2019-10-01 | 2.3 |
Note: Adjusted for striking workers: https://www.bls.gov/ces/publications/strike-report.htm.
Source: EPI analysis of Bureau of Labor Statistics' Current Employment Statistics public data series
This obvious slowdown in manufacturing employment is troubling in itself, but the reason to look more closely at manufacturing isn’t simply because it’s a significant share of the economy (10% of private-sector employment) and historically has been a place for decent non-college jobs—largely due to the relatively high levels of unionization in that sector in the past. Manufacturing is one of the most cyclical sectors, bested only by construction (among major industries) in its prediction of upcoming economic slowdowns. And, construction isn’t looking too hot either. Average monthly construction job growth so far in 2019 is about half as fast as it was in 2018. This does not mean we are necessarily headed toward a recession, but this is certainly an indicator to keep an eye on in coming months.
The Federal Reserve is doing the right thing by cutting the federal funds rate this year, helping to keep the economy from stalling and for workers to hopefully see stronger wage growth. The figure below shows year-over-year nominal wage growth over the last several years. After rising to 3.4% in February 2019, the rate of growth has been tapering off. Wage growth is now back down to 3.0% over the year, significantly lower than levels consistent with inflation targets and productivity potential. This is slower than expected given that the unemployment rate has been at or below 4.0% for 20 months in a row. All else equal, the relative scarcity of workers should be driving up wages as employers have to compete to attract and retain the workers they want.Read more
OECD highlights temporary labor migration: Almost as many guestworkers as permanent immigrants
The 2019 edition of the Organization for Economic Cooperation and Development’s (OECD) annual International Migration Outlook report included a new chapter, “Capturing the ephemeral: How much labour do temporary migrants contribute in OECD countries?” It’s a good question, and one that had not yet been answered.
There is a dearth of data on temporary labor migration programs (TLMP) or schemes—aka guestworker programs, where migrants are employed temporarily in a country outside their own—and it hinders the ability of policymakers to make informed decisions. The OECD declared TLMPs are “a core concern in the public debate across OECD countries” but warns that their impacts are “understudied.” This information deficit exists despite the fact that TLMPs are controversial and make up an increasing share of labor migration, and in the United States in particular have been at the center of debates about how to reform the U.S. immigration system.
Why are TLMPs controversial and at the center of public debates? First, their size. One of OECD’s key findings is that the 4.9 million temporary labor migrants that entered OECD countries in 2017 is “almost as many… as permanent migrants in all categories combined.” Ignoring temporary labor migration in the OECD means ignoring nearly half of all migration.
Many employers want larger TLMPs and fewer regulations governing their use. But there are high economic, social, and psychological costs for the migrant workers who participate in temporary programs, including frequent human rights violations suffered in both countries of origin and destination. Further, some abuses that are technically legal are facilitated by the legal frameworks of TLMPs. In most TLMPs, employers control the visa status of their temporary migrant employees or “guestworkers”—which means getting fired makes them deportable. In part, that’s why TLMPs have been called things like “The New American Slavery.”
TLMPs raise technical issues that are not easily resolved. For example: Which industries are permitted to hire migrant workers? How will appropriate numerical limits in TLMPs be determined? What rights will migrants have once they’ve been admitted into receiving country labor markets? Can they bring their families? Will migrants be tied to one employer or be allowed to change jobs and employers? How will receiving country governments ensure that migrants return after their employment contracts end, or will migrants be allowed to become permanent residents? Do citizens in receiving countries have first preference for jobs that employers want to fill with migrants? Will migrants be paid the same wages as similarly situated local workers?Read more